Mobile App Design
UI/UX
2026
01Introduction

About Project

About the Client

Guyana’s only indigenous private-sector bank, serving individuals and businesses since 1994 from eight branches.

Client Requirement

A mobile app for everyday banking, plus a revamp of the web banking system on one shared design language.

02Overview

Scope of Work

Desktop Revamp

The existing web banking system, rebuilt on a modern, scalable design system.

24screens
3weeks

Mobile App Design

A new iOS and Android app for everyday banking, designed mobile-first.

38screens
4weeks
03Problem Statement

The Problem

Problem 01

Customers couldn’t bank digitally without hassle. Routine tasks still meant a trip to the branch.

Problem 02

The bank’s current system couldn’t scale to a modern interface.

04Desk Research

Understanding the friction

Going into 2026, 81.7% of Guyanese were online: 684,000 people ready to bank digitally.

However, no app let them bank without hassle.
DataReportal · Digital 2026: Guyana
Two people reviewing work on a laptop
05Solution Statement

The Solution

Solution 01

A mobile app that puts everyday banking in every customer’s pocket.

Solution 02

A revamped, scalable design system shared across web and mobile.
Two people chatting over coffee
06Who we designed for

Target Audience

Who?

Why?

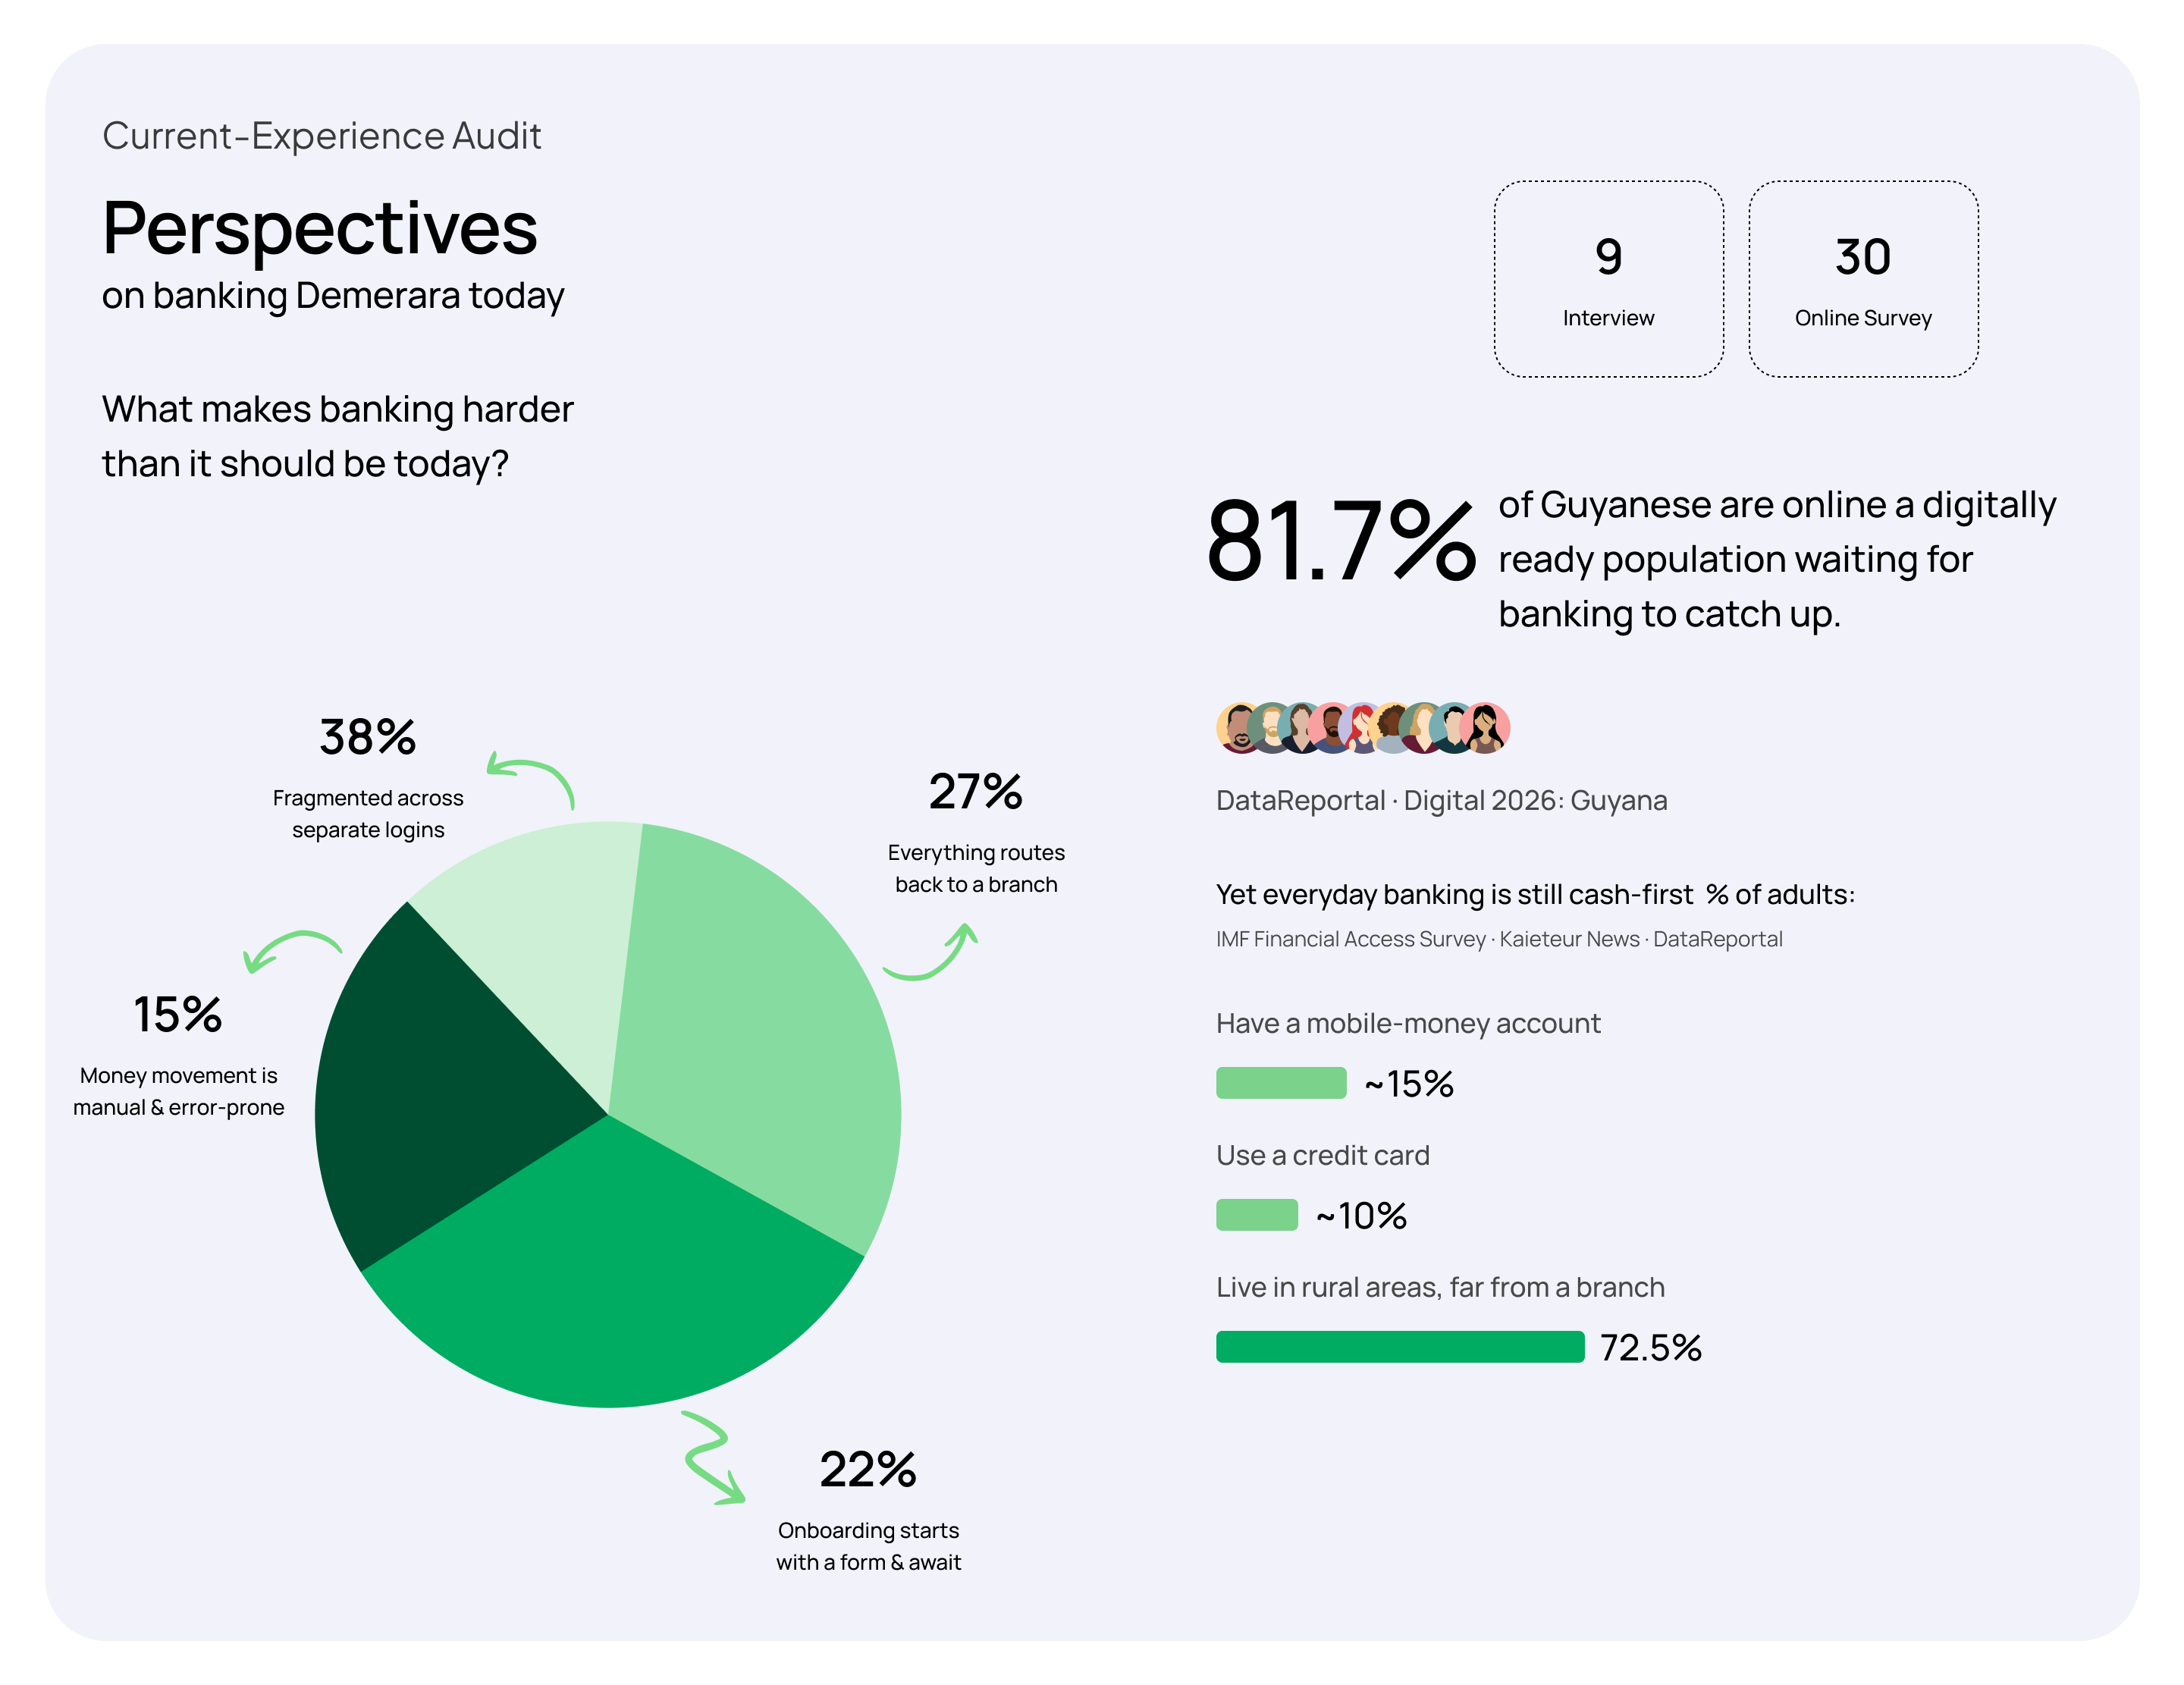
Pie chart: 38% fragmented across separate logins, 27% everything routes back to a branch, 22% onboarding starts with a form and a wait, 15% money movement is manual and error-prone
07Current-Experience Audit

Perspectives

On banking with Demerara today.

What makes banking harder than it should be today?

9Interviews
30Online Survey

Research by Demerara Bank, shared with the design team

81.7%

of Guyanese are online, ready for digital banking.
DataReportal · Digital 2026: Guyana
Yet everyday banking is still cash-first · % of adults:
US ITA · IMF Financial Access Survey · DataReportal
Have no bank account
~40%
Have a registered mobile-money account
~15%
Live in rural areas, far from a branch
72.5%
Hands writing in a notebook next to a laptop

What’s the most frustrating part of banking with your bank today?

Going into a branch for routine tasks
34%
Juggling separate logins for accounts & cards
28%
Live in rural areas, far from a branch
22%
Waiting on applications, with no way to track them
16%
How Guyana banks today
81.7%Are online
15%Have mobile money
~40%Have no bank account

Sources: DataReportal, Digital 2026: Guyana (81.7% online) · IMF Financial Access Survey (registered mobile-money accounts ≈15% of adults, 2024) · US International Trade Administration, 2026 (~4 in 10 adults unbanked)
Phone scanning a QR code
Designer in front of a board of sketches
Designer pinning notes on a wireframe wall
Woman frowning at a laptop
08Qualitative research

Interview Questions

How people bank day to day, and where it lets them down.

Walk me through the last time you moved money or paid a bill online. What felt easy and what didn’t?

When you open a banking app, what’s the first thing you look for? How quickly do you find it?

Have you ever abandoned a task and called the bank or visited a branch instead? What made you switch?

How confident do you feel that a transfer or payment has actually gone through?

What makes a banking app feel trustworthy or untrustworthy to you?

Which everyday banking task do you wish were far simpler than it is today?

09Observations

Key Insights

Real voices from the research.

“I can never find where to start. I know the bank can do it, I just can’t find the button.”
Ananya
Retail customer

“There’s so much on the screen at once. I always double-check that I did it right before I close it.”
Ravi
Small business owner

“It looks old, so a part of me doesn’t fully trust it with big transfers. I’d rather go in.”
Maria
Salaried professional
10Market Research

Competitor Analysis

A SWOT of Demerara’s digital offer before the redesign.

Strength
Weakness
Opportunities
Threats
Complete banking catalogue already online
20+ services in the app
Established, trusted institution
Serving Guyana since 1994
Real transactional depth
Transfers, loans, deposits, wires
Only indigenous private-sector bank
A strong local identity
Three web portals plus an app
Separate logins for personal, corporate and cards
Dated, dense interface
“It looks old, so I don’t fully trust it”
Paper-bound onboarding
Scanned uploads and fillable PDFs
Legacy system can’t scale
No foundation for a modern UI
81.7% of Guyanese online
Median age 26, mobile-first
Real-time payments on the way
FAST PAY announced for June 2026
Mobile-money accounts up 3× since 2020
Appetite for digital money
~4 in 10 adults unbanked
Room to grow through inclusion
Rivals digitising faster
Regional banks and mobile wallets
Customers compare to their best app
Not only to other banks
Fraud and security fears
One bad experience erodes trust
A rising national bar for digital
Government push for digital payments

Weaknesses + opportunities = the brief

Biggest lever: one login, one system

Trust must be visible, not assumed
11User Persona

User Personas

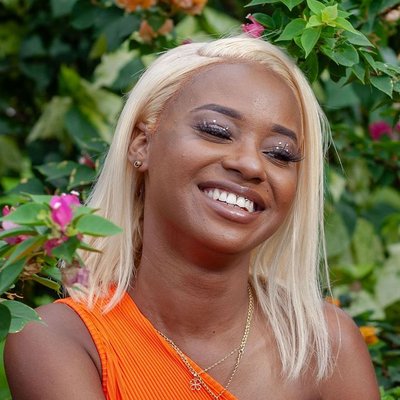
Priya Persaud

Priya Persaud

Age:34
Occupation:Small-business owner (retail & import)
Location:Georgetown, Guyana
Tech Literate:High
User goal:Personal & business banking in one app, no branch trips.

“I’m on my phone all day for the business. I just need my bank to keep up, instead of sending me to a line for something I could tap in a minute.”

Practical Time-poor Driven Mobile-first
Pains

  • Juggles separate logins for personal, business and card accounts.
  • Loses hours to branch queues for routine tasks.
  • Paying suppliers and sending wires means copying long bank details by hand.

Goals

  • Manage every account and card in one place, and move money in seconds with clear confirmation.
  • Plan an SME loan and book the branch visit from her phone, no queue.
Shanice

Shanice

Age:27
Occupation:Registered Nurse
Location:Georgetown, Guyana
Tech Literate:High
User goal:Everyday banking in a few taps between shifts.

“I work long shifts. I need to bank in a few taps on my phone, and actually trust that it went through.”

Busy Cautious Practical Mobile-first

Pains

  • Long shifts leave no time for branch visits.
  • Current online banking feels dated and confusing.
  • Never quite sure a transfer or bill payment actually completed.

Goals

  • Check balances and pay bills quickly on her phone.
  • Send money to family instantly, with a clear “it’s done” confirmation.
  • Feel her money and data are secure, and open a fixed deposit or apply for a card without going in.
12Qualitative Research

Affinity Diagram

What we heard, what users need, what we built.

User Needs

Reach any task in as few steps as possible, without hunting.

A shallow information architecture with quick actions surfaced up front.

Know for certain that a payment or transfer went through.

Designed loading, filled, and confirm states across every money-movement flow.

Feel that my money and data are in safe hands.

A premium visual language with visible security cues and secure authentication.

Project Solution

13Brainstorming

Product Goals

Four goals that shaped every screen.

Simplify the routine

Make transfers, bill payments, and account monitoring the fastest, most obvious things to do.

Reduce cognitive load

Replace dense screens with clear hierarchy, predictable patterns, and progressive disclosure.

Build visible trust

Use a secure, modern, premium language so people feel their money is in safe hands.

Unify the ecosystem

One design system and one mental model — consistent across web, mobile, and every service.
14Structure

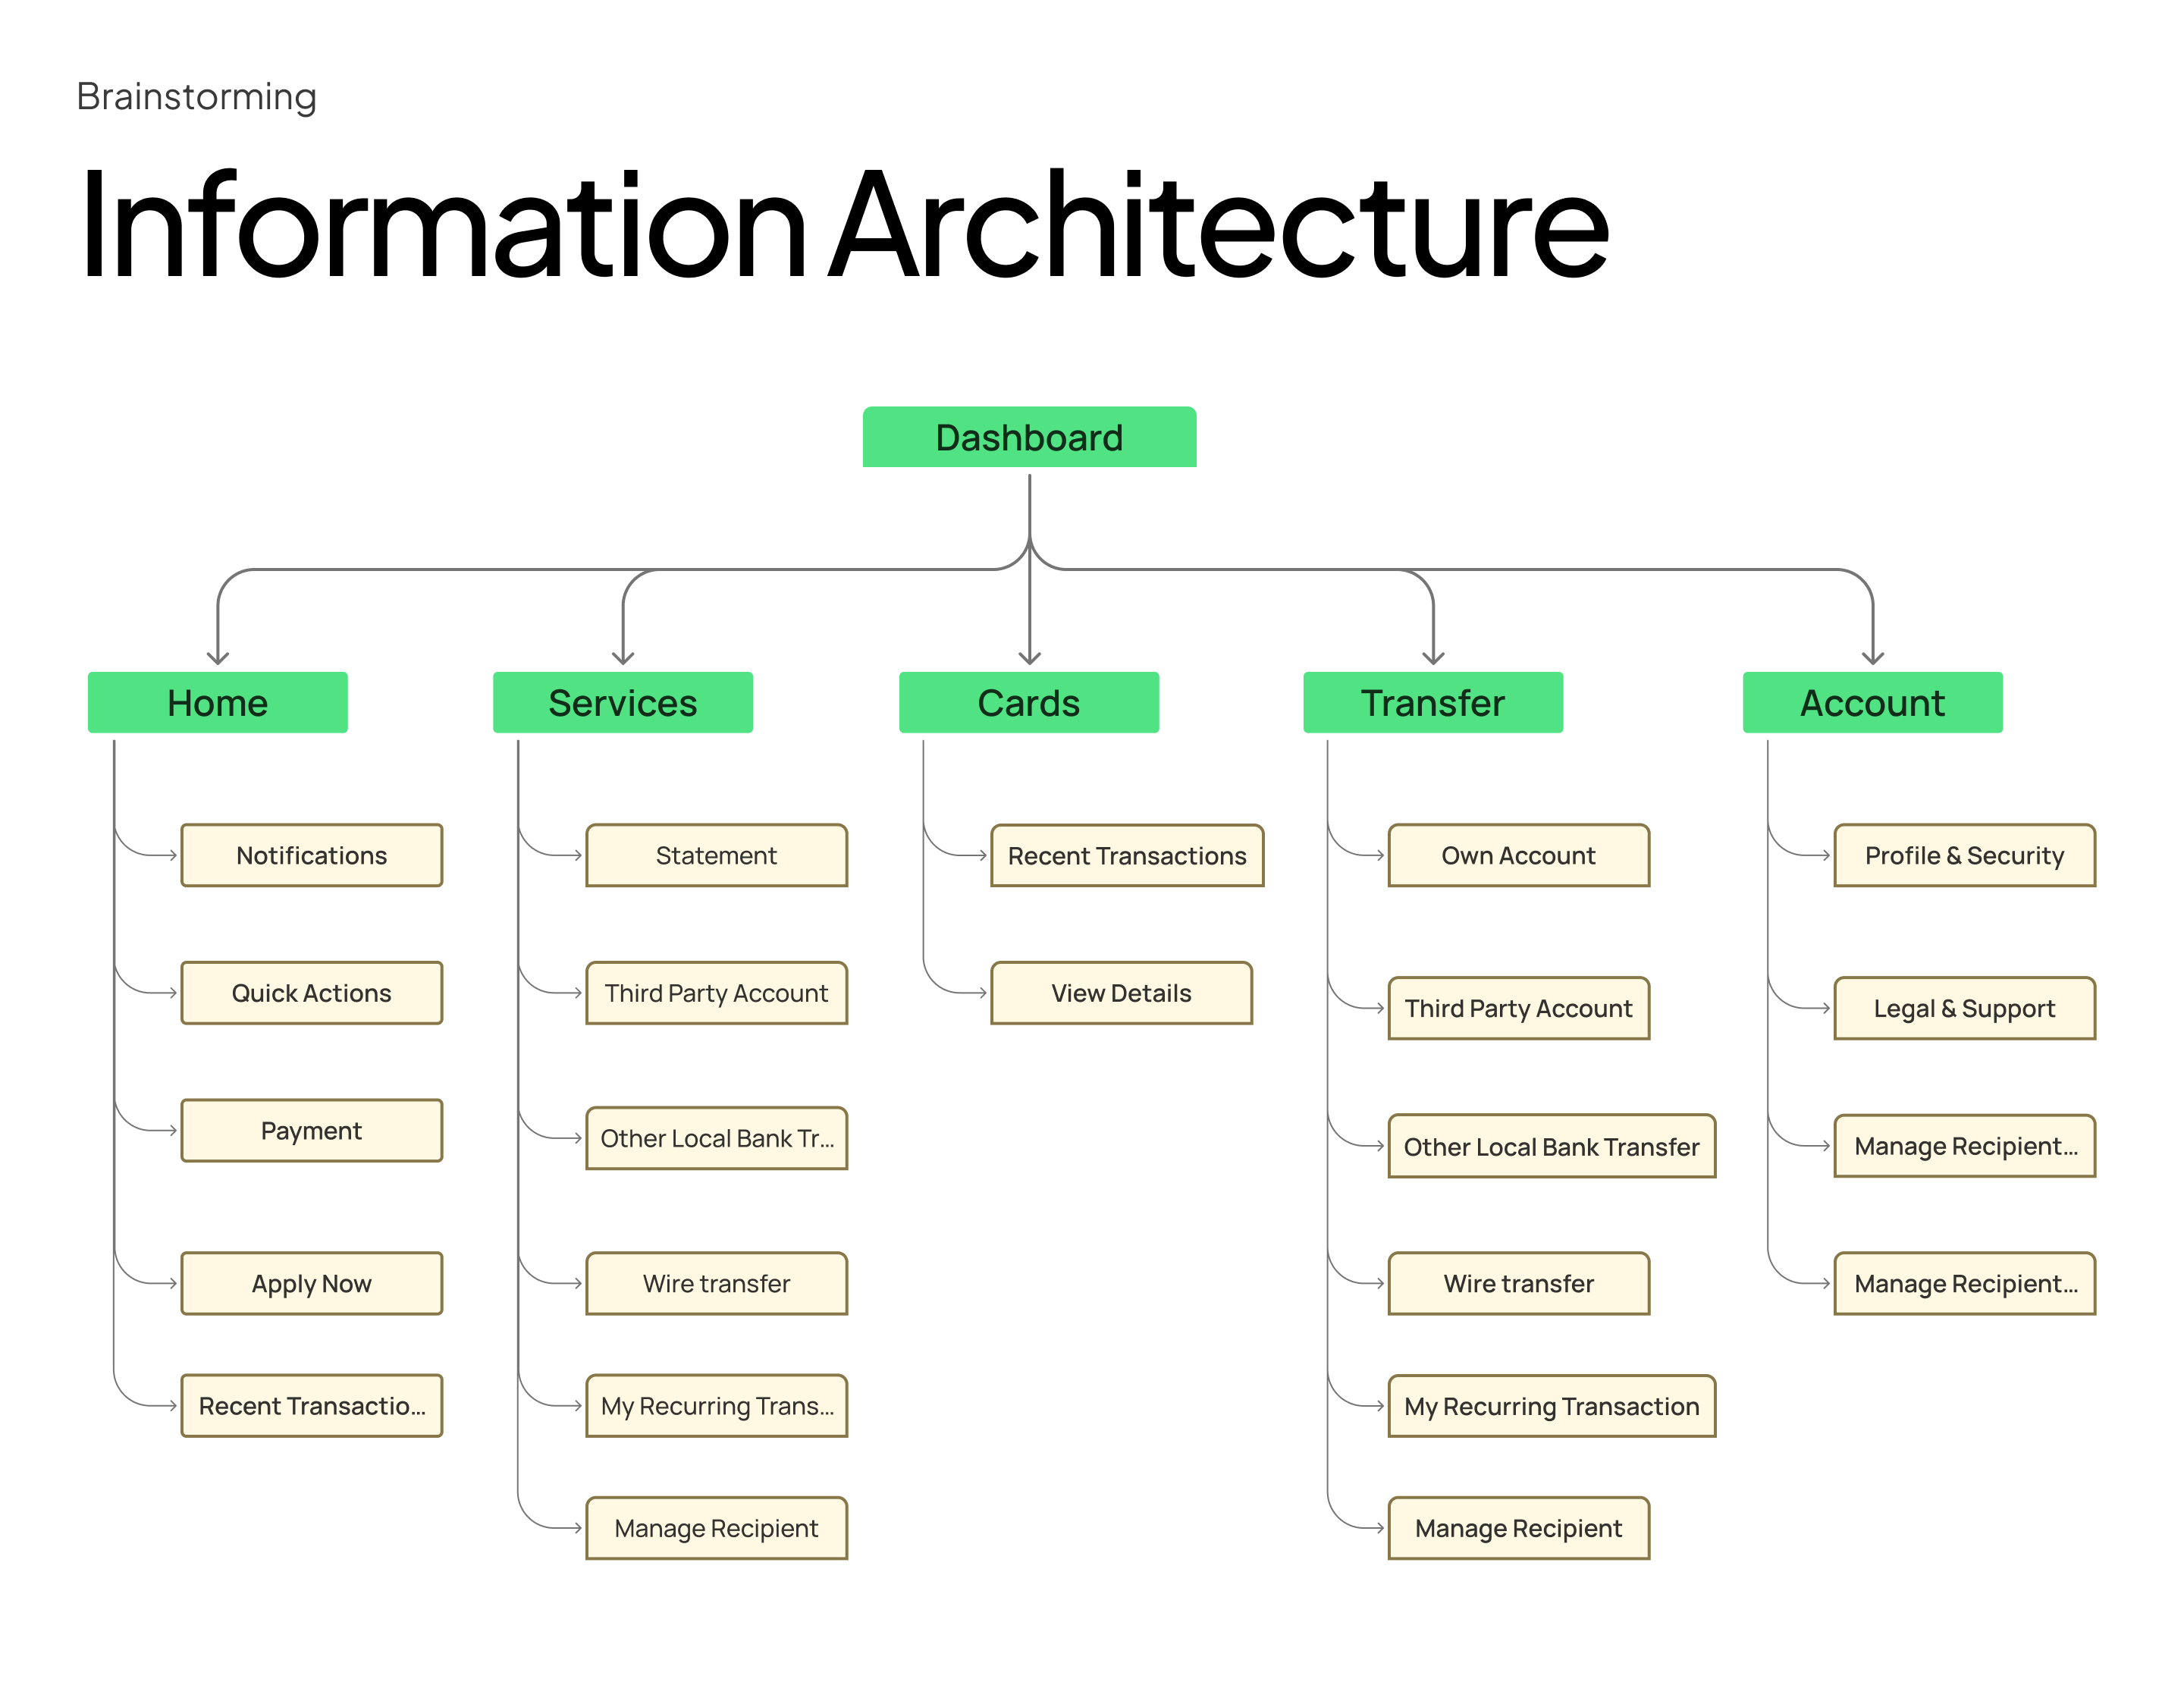
Information Architecture

Information architecture: Dashboard branches into Home, Services, Cards, Transfer and Account, each with its sub-pages

Swipe to explore the full map →

15Low Fidelity

Wireframes

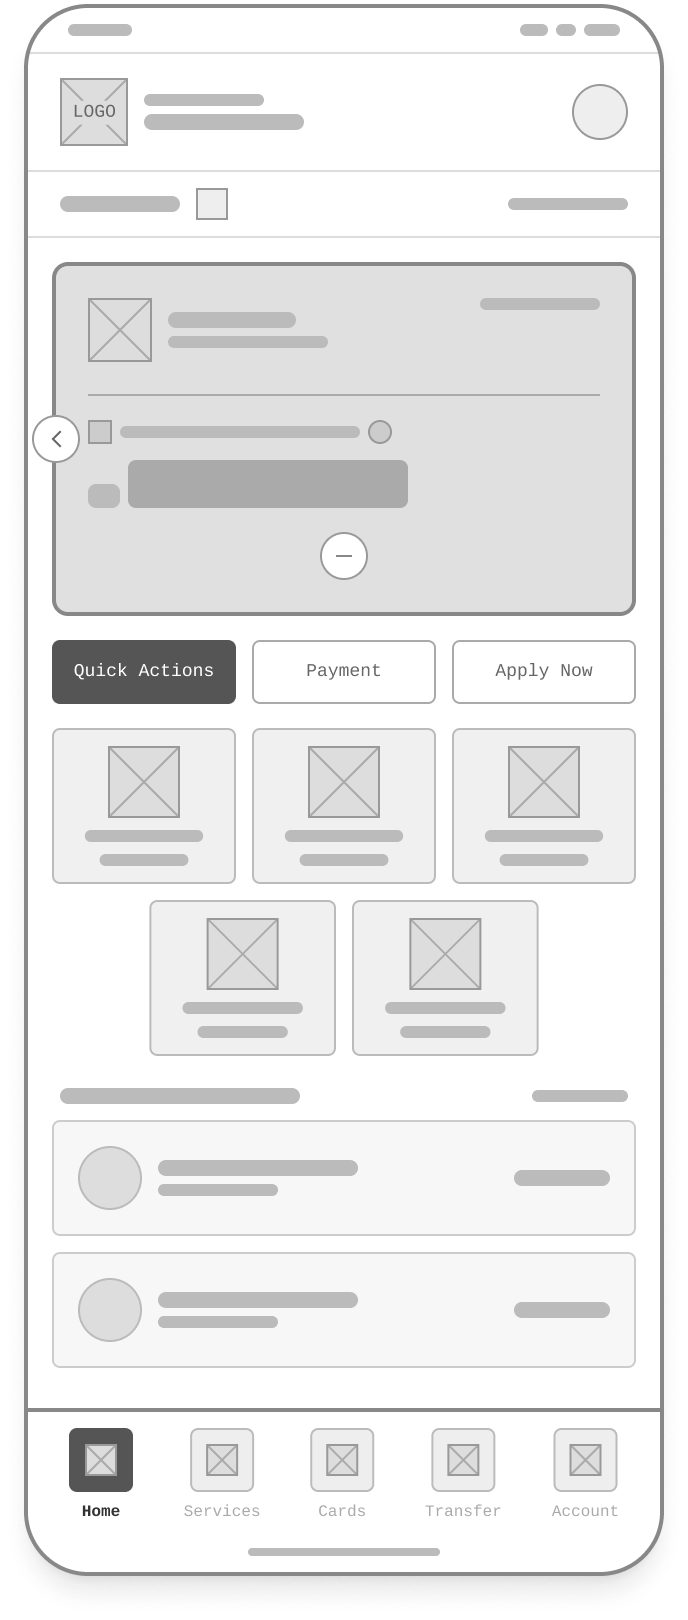
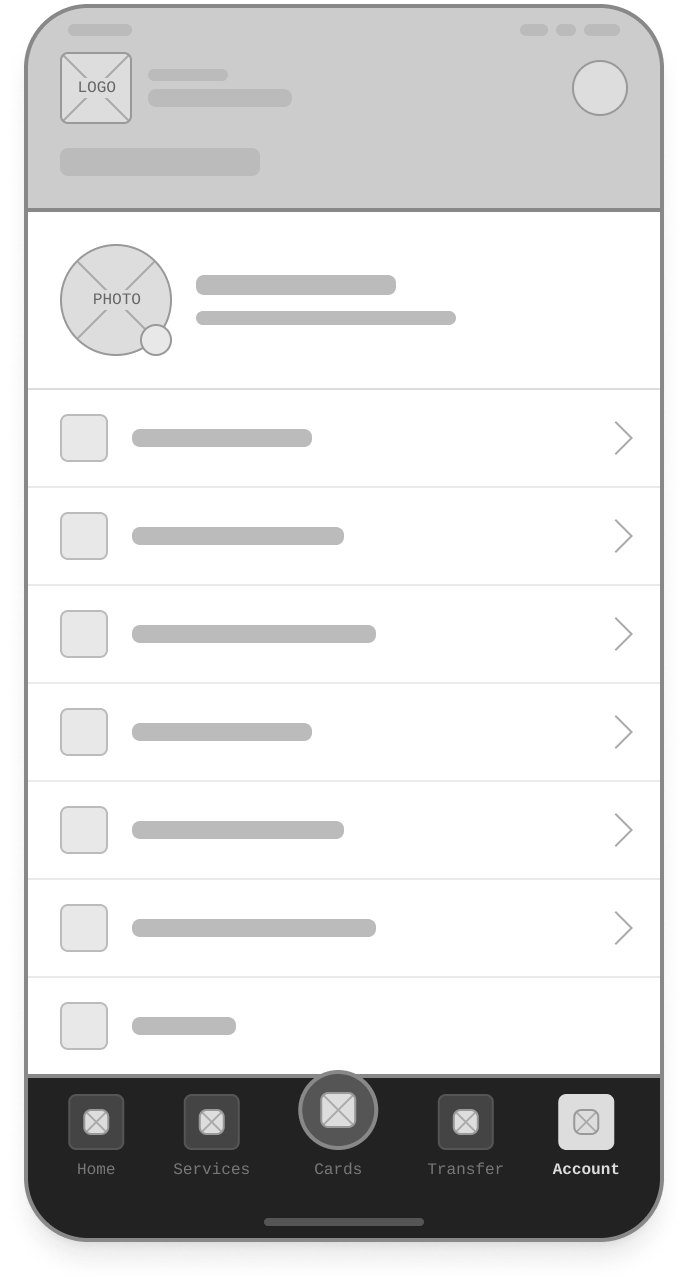
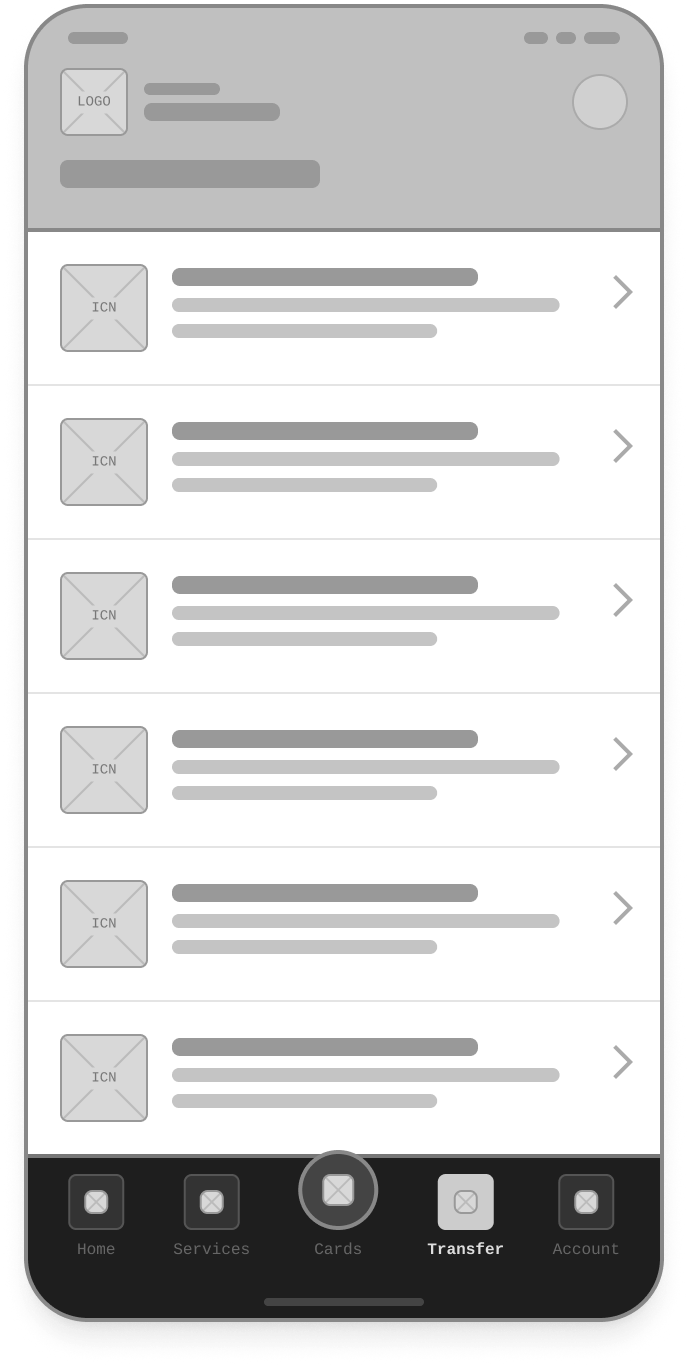
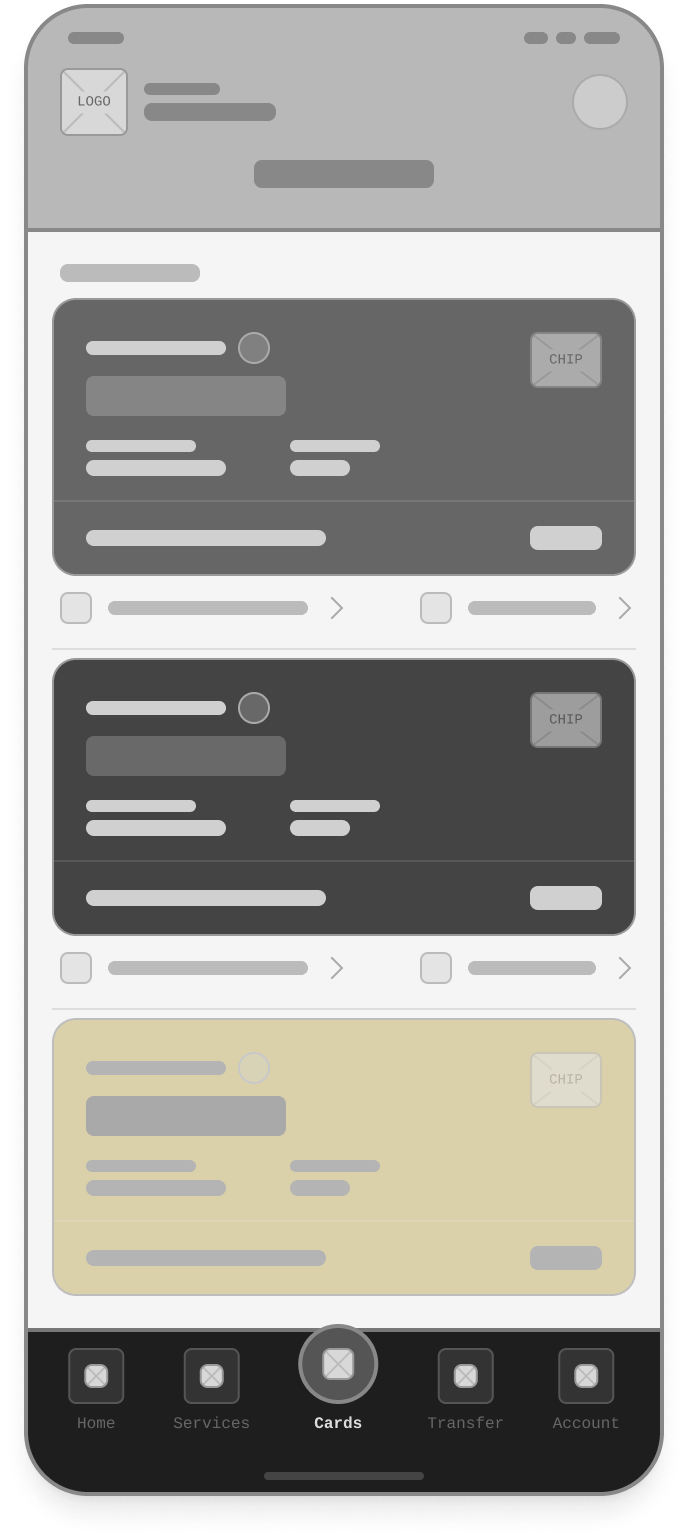
Home wireframe Account wireframe Transfer wireframe Cards wireframe Header & profile Account switcher Quick-action grid Recent transactions Bottom navigation Profile block Settings list Transfer header Transfer types Card & controls Premium tier card

Swipe to see all four wireframes →

16Style Guide

Colour

Built from Demerara’s own green and gold. Deep green for trust, bright green for growth, gold for premium moments and key actions. Click a swatch to copy it.

Demerara GreenPrimary · #004E32
Growth GreenSecondary · #00A155
Heritage GoldAccent · #D09106

Neutrals

Heading#121414
Subheading#434848
Body#5B6262
Border#D2E0E0
Surface#F4F4F4
Base#FFFFFF

States & Actions

Success#009262
Success Light#84DFC1
Danger#E01507
Golden Button#E1A730
Golden Light#FED071
Teal#1EA296
17Style Guide

Typography

Red Hat Display runs through every screen. Its clear, distinct figures keep balances easy to read, and it stays legible at small sizes on budget phones.

Aa
Red Hat Display
Screen title
20 · SemiBold
$2,656,663.60
18 · Bold · balances
Section heading
16 · SemiBold
Body & input text
14 · Medium
Labels & captions
12 · Medium
Tab bar labels
10 · SemiBold

Banking anywhere, anytime. Demerara’s own promise, now in every customer’s pocket.
18The solution

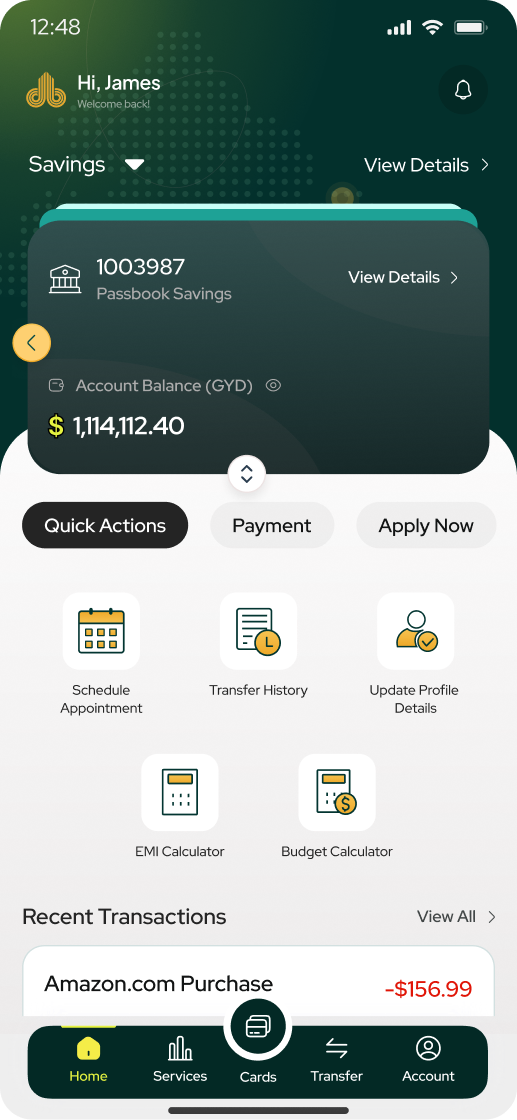
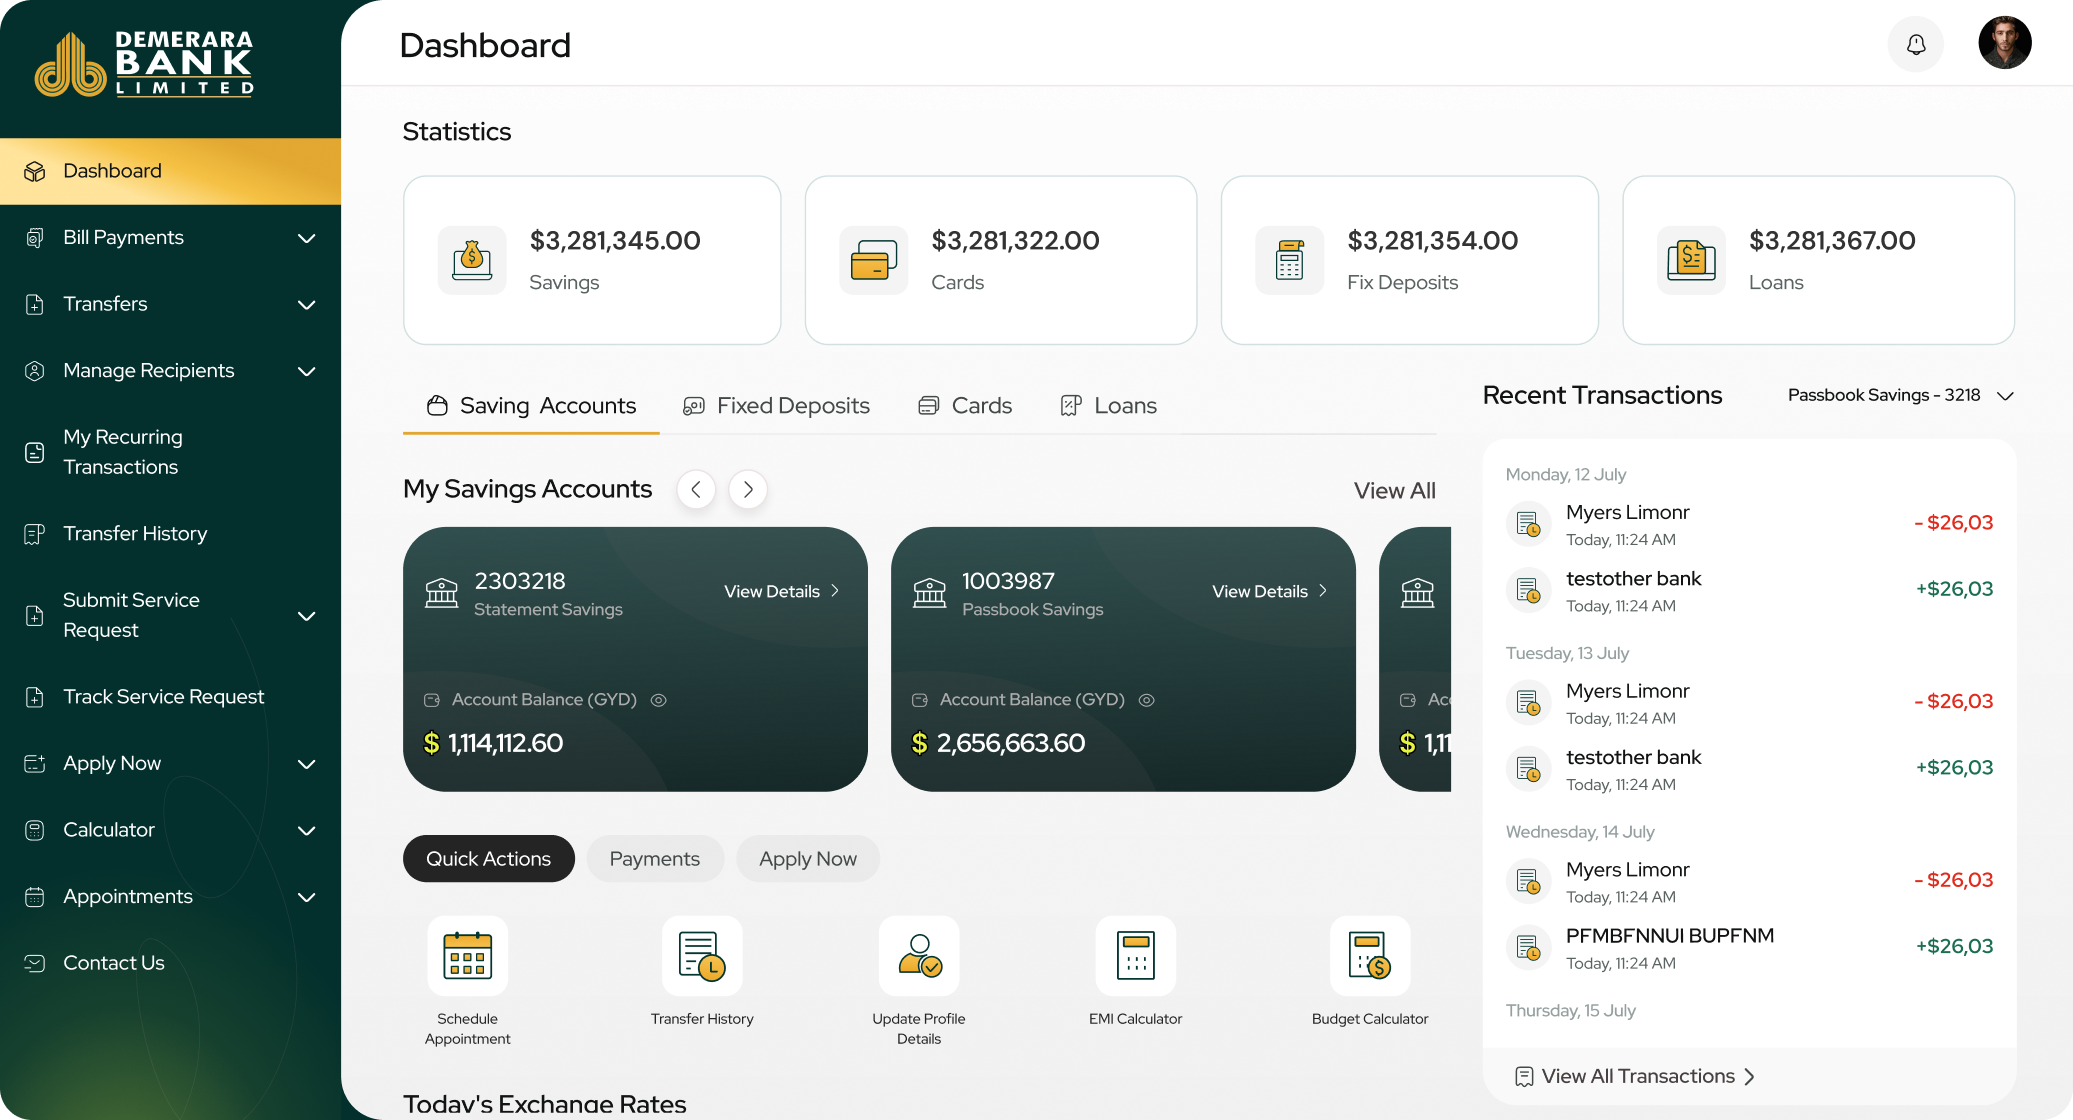
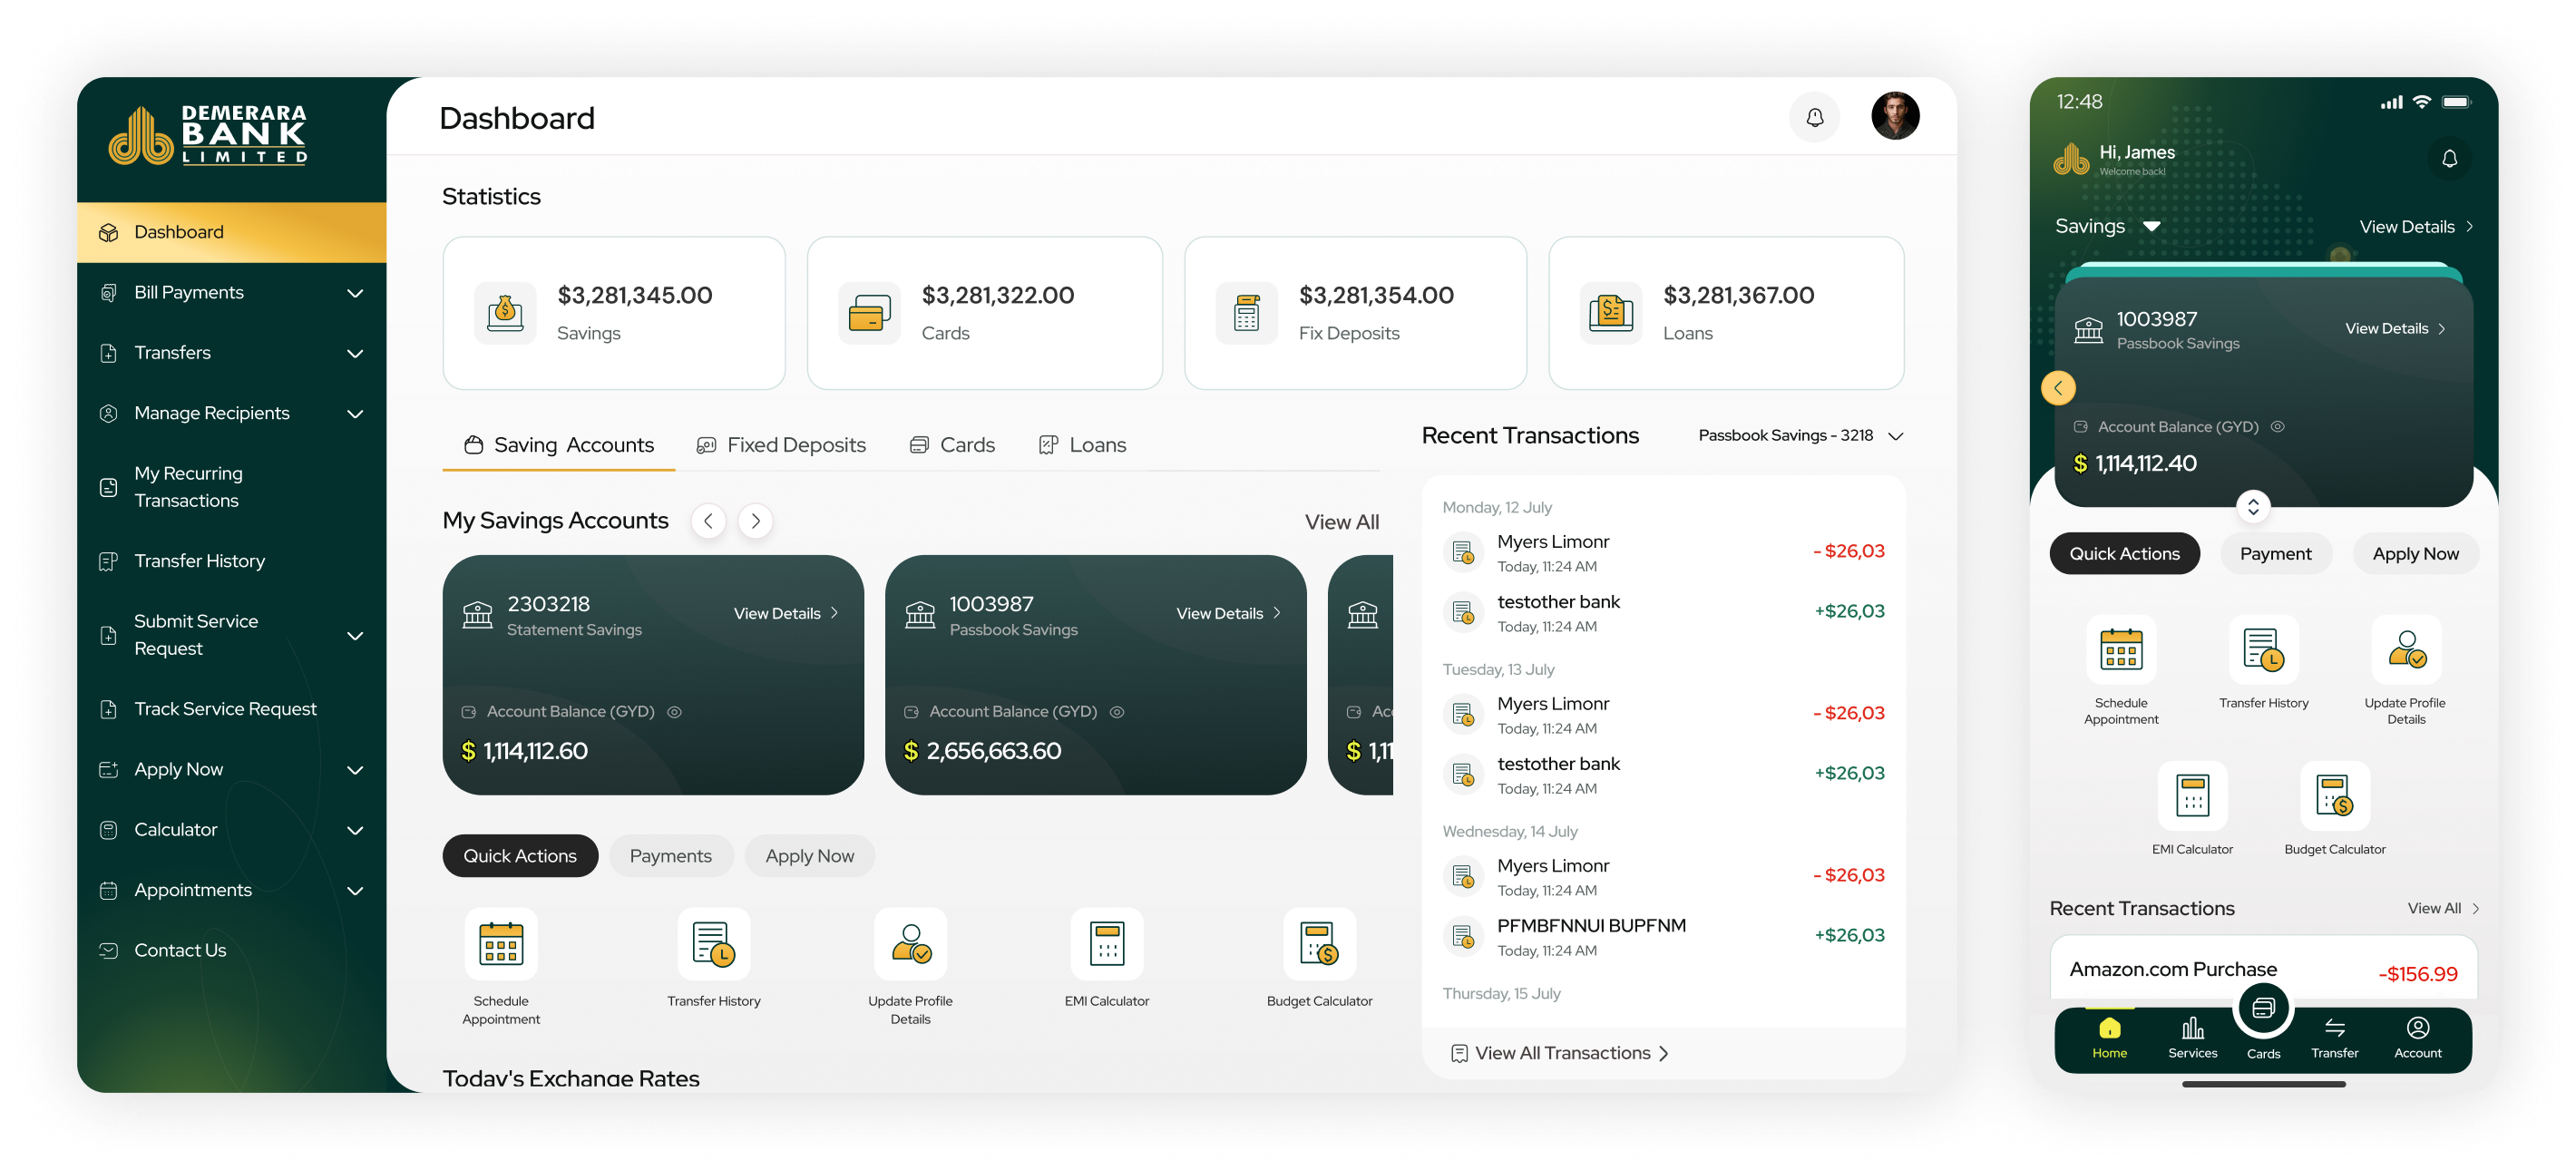
Dashboard & Home

Web dashboard and mobile home screen
Mobile home screenWeb banking dashboard

Swipe to see each screen →

19The solution

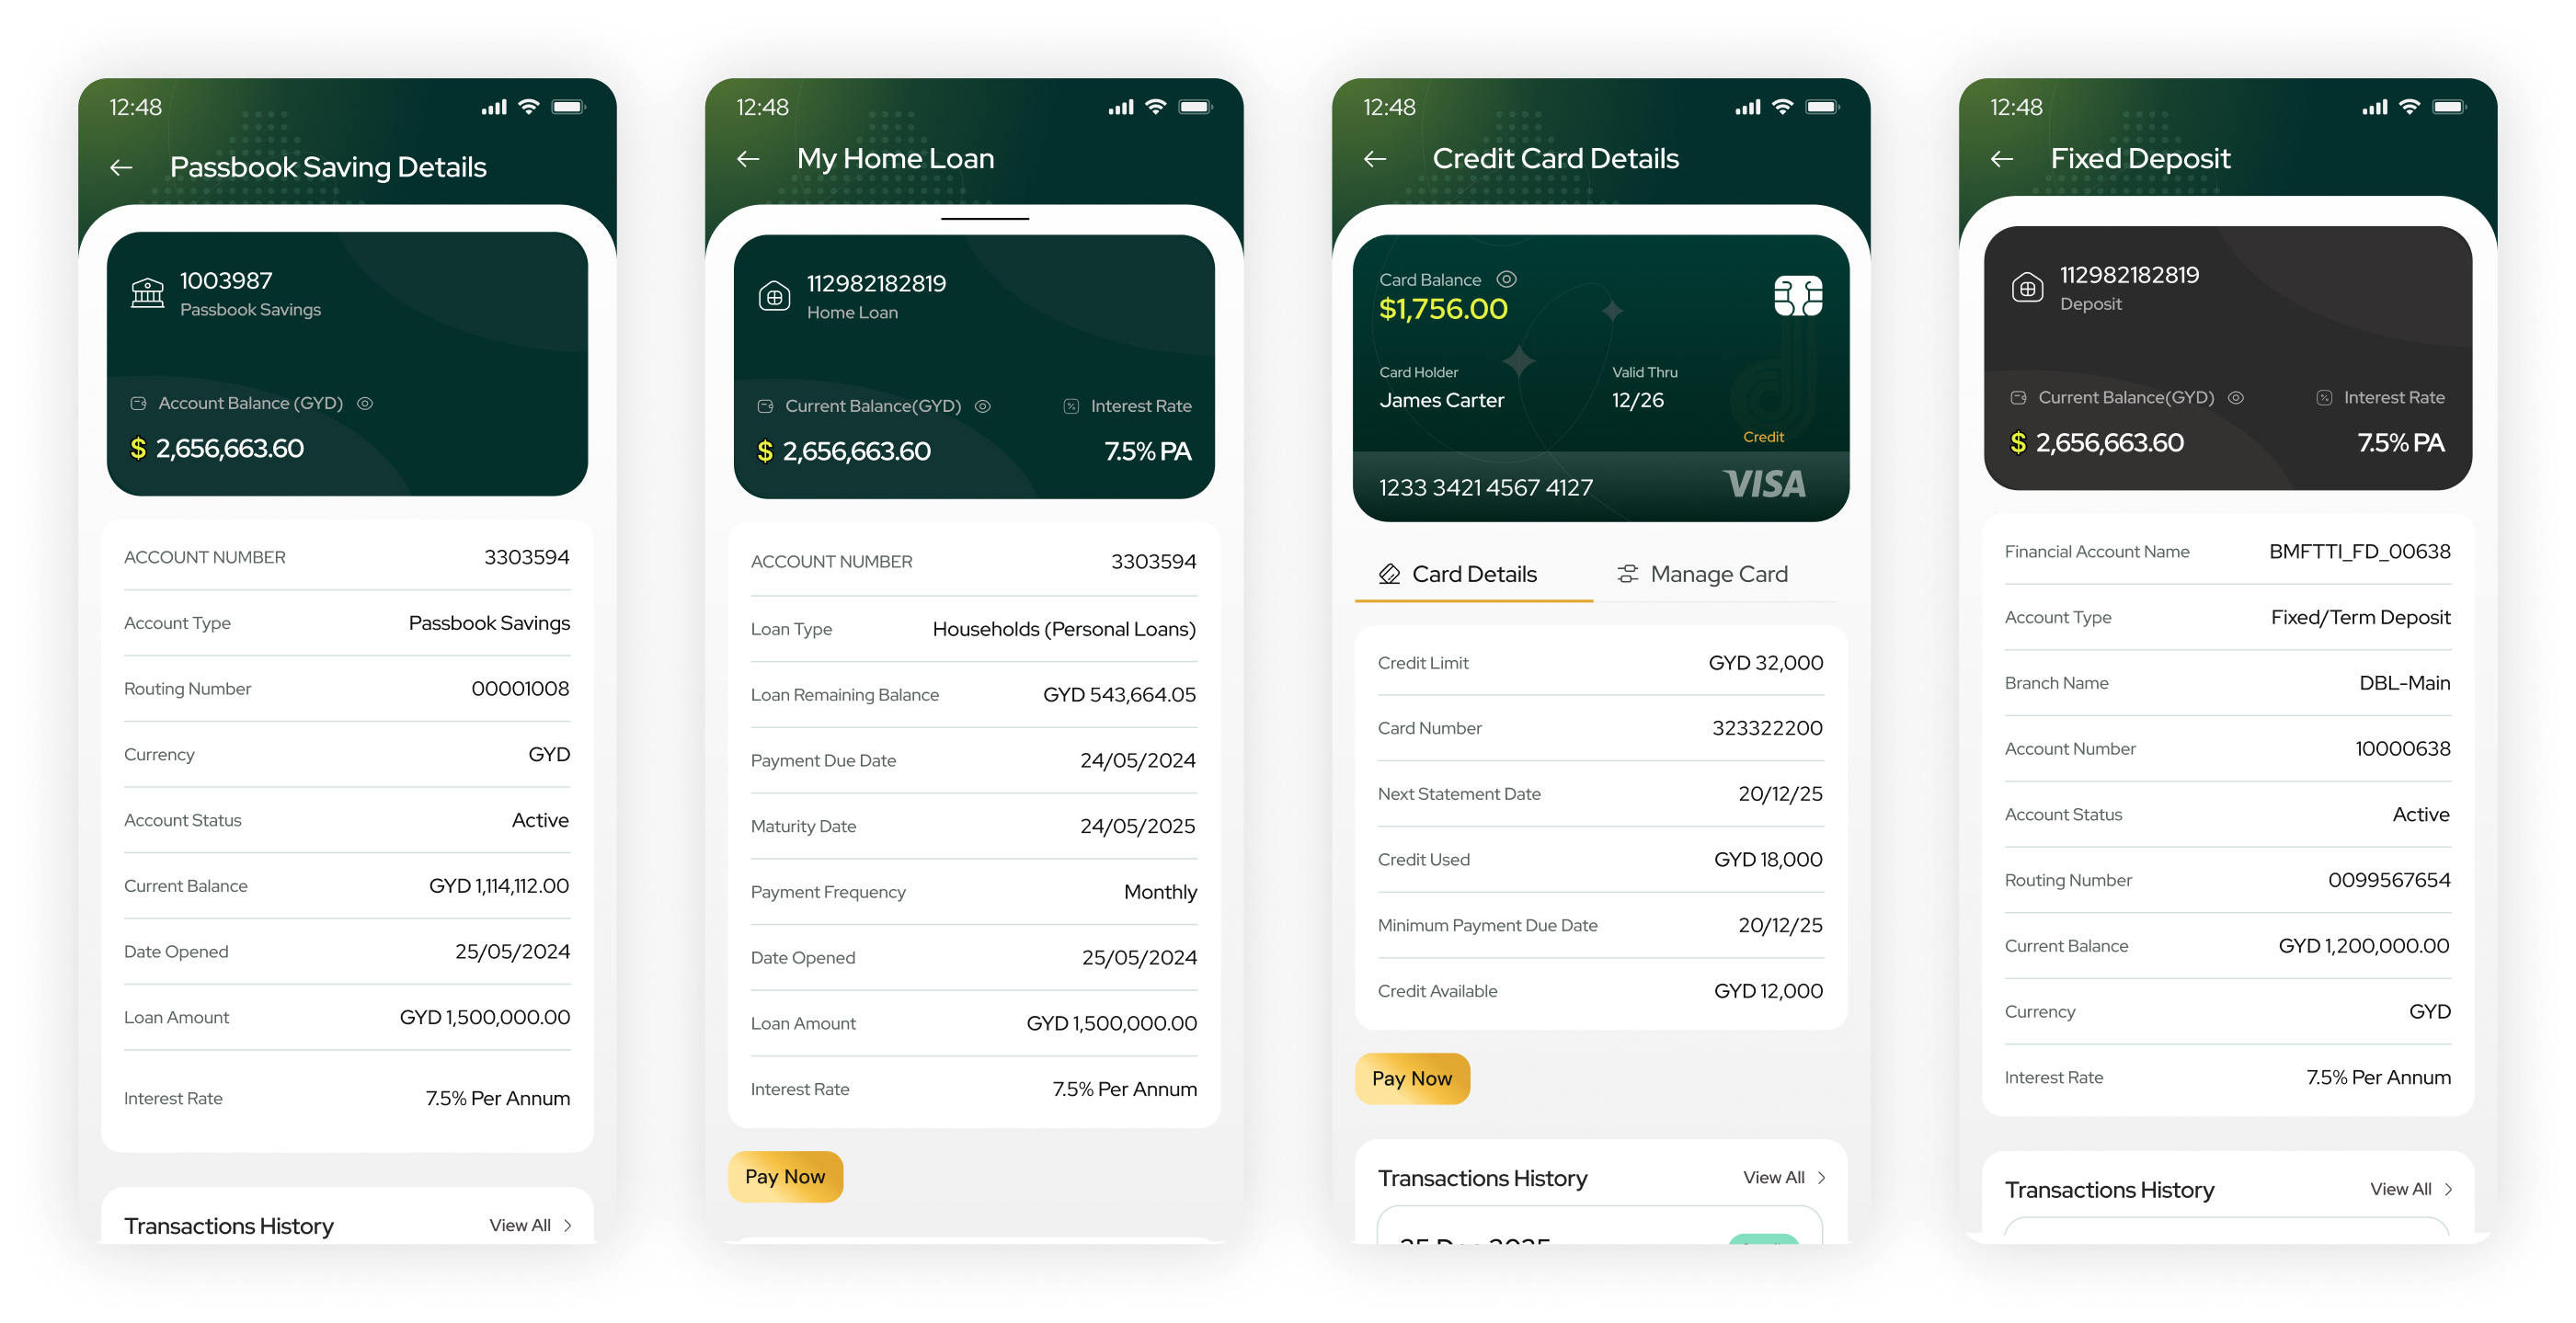
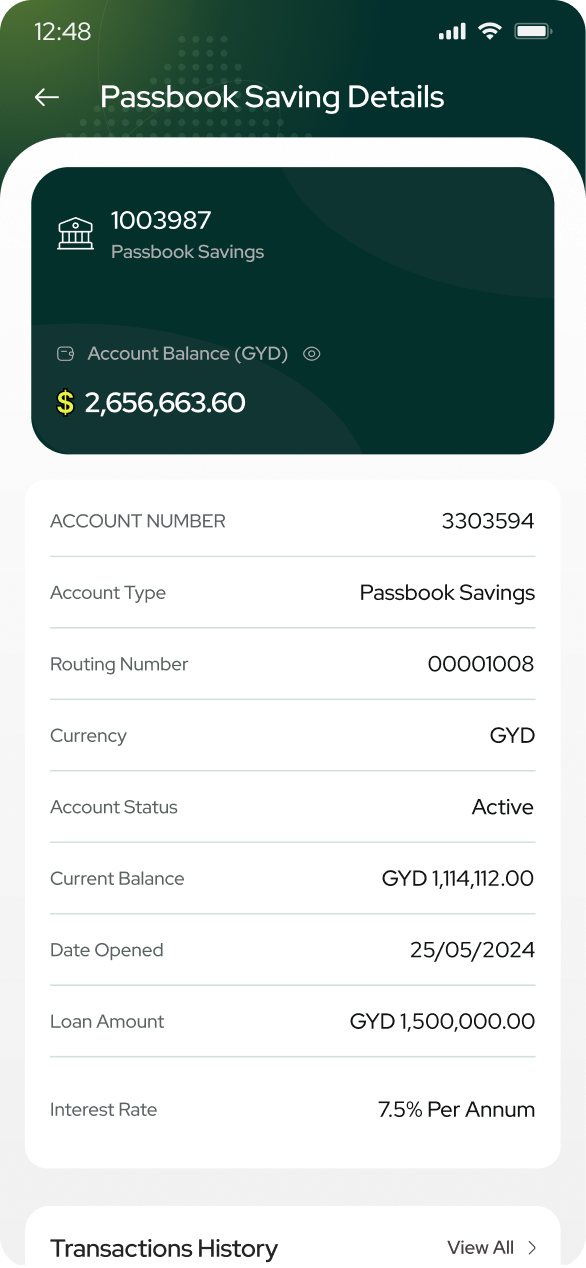
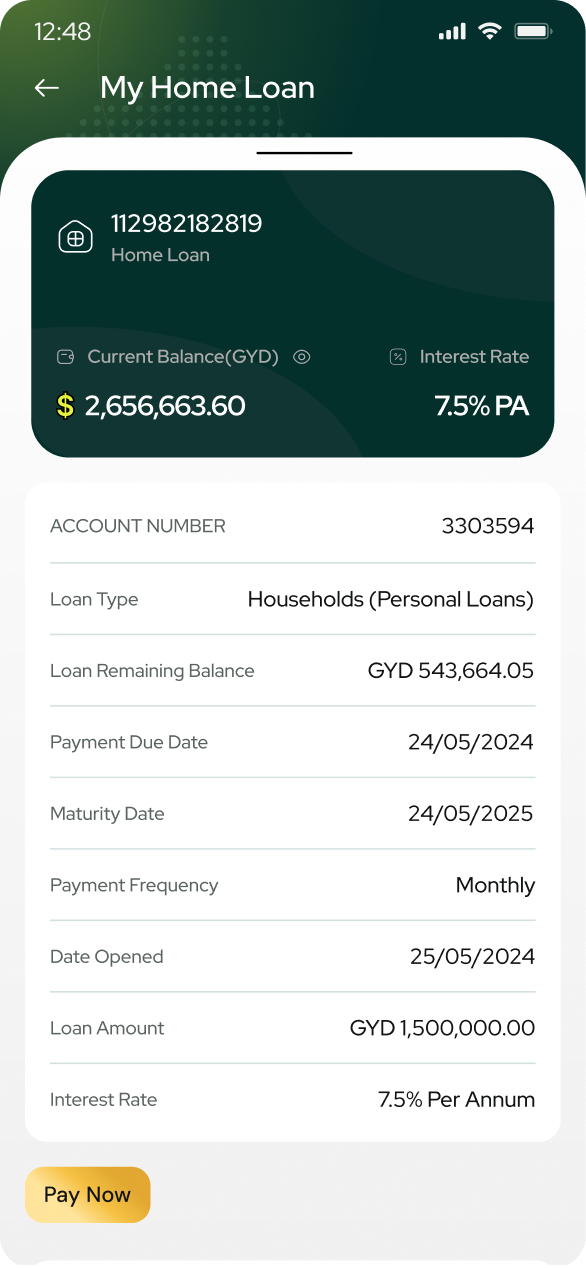
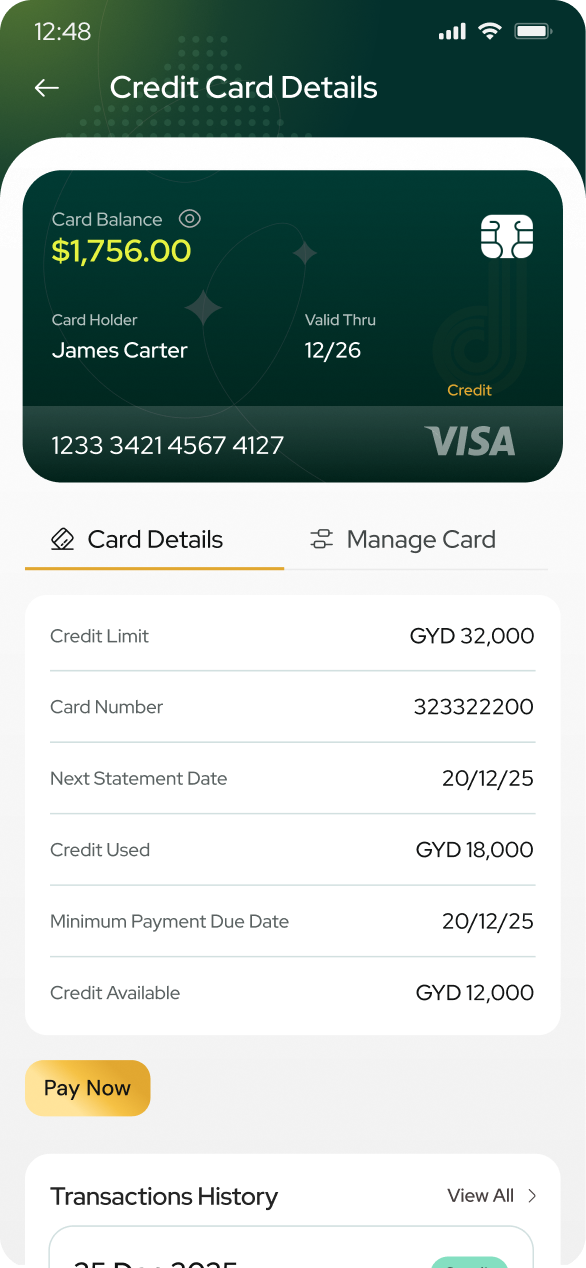
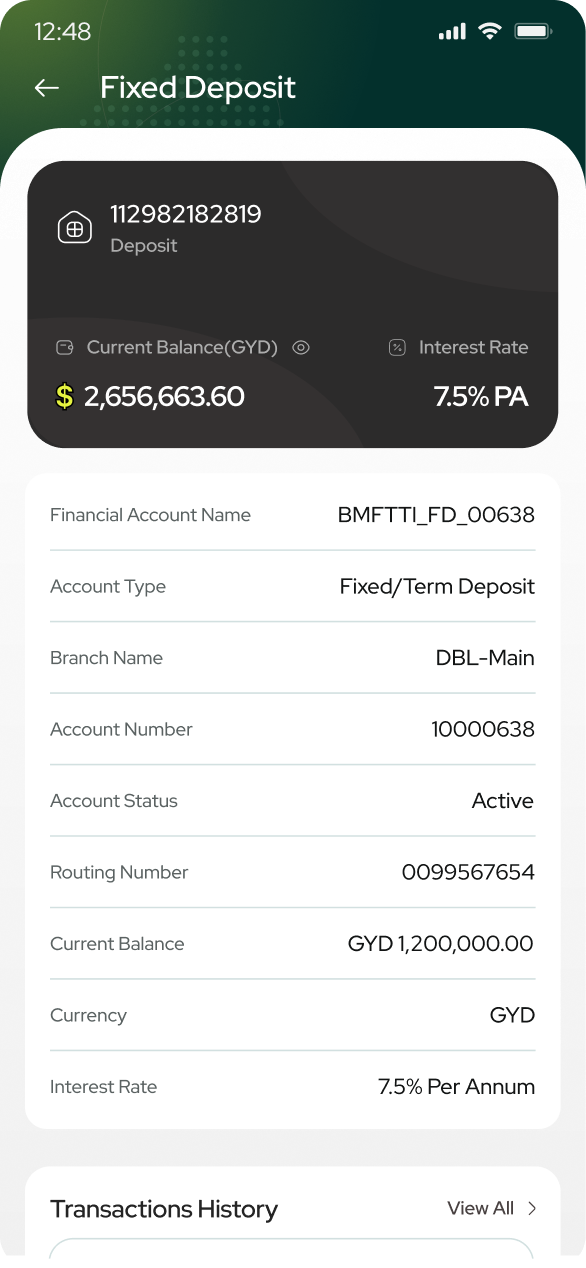
Accounts at a Glance

Passbook savings, home loan, credit card and fixed deposit detail screens
Passbook savings screenHome loan screenCredit card screenFixed deposit screen

Swipe to see each screen →

20The solution

Moving Money

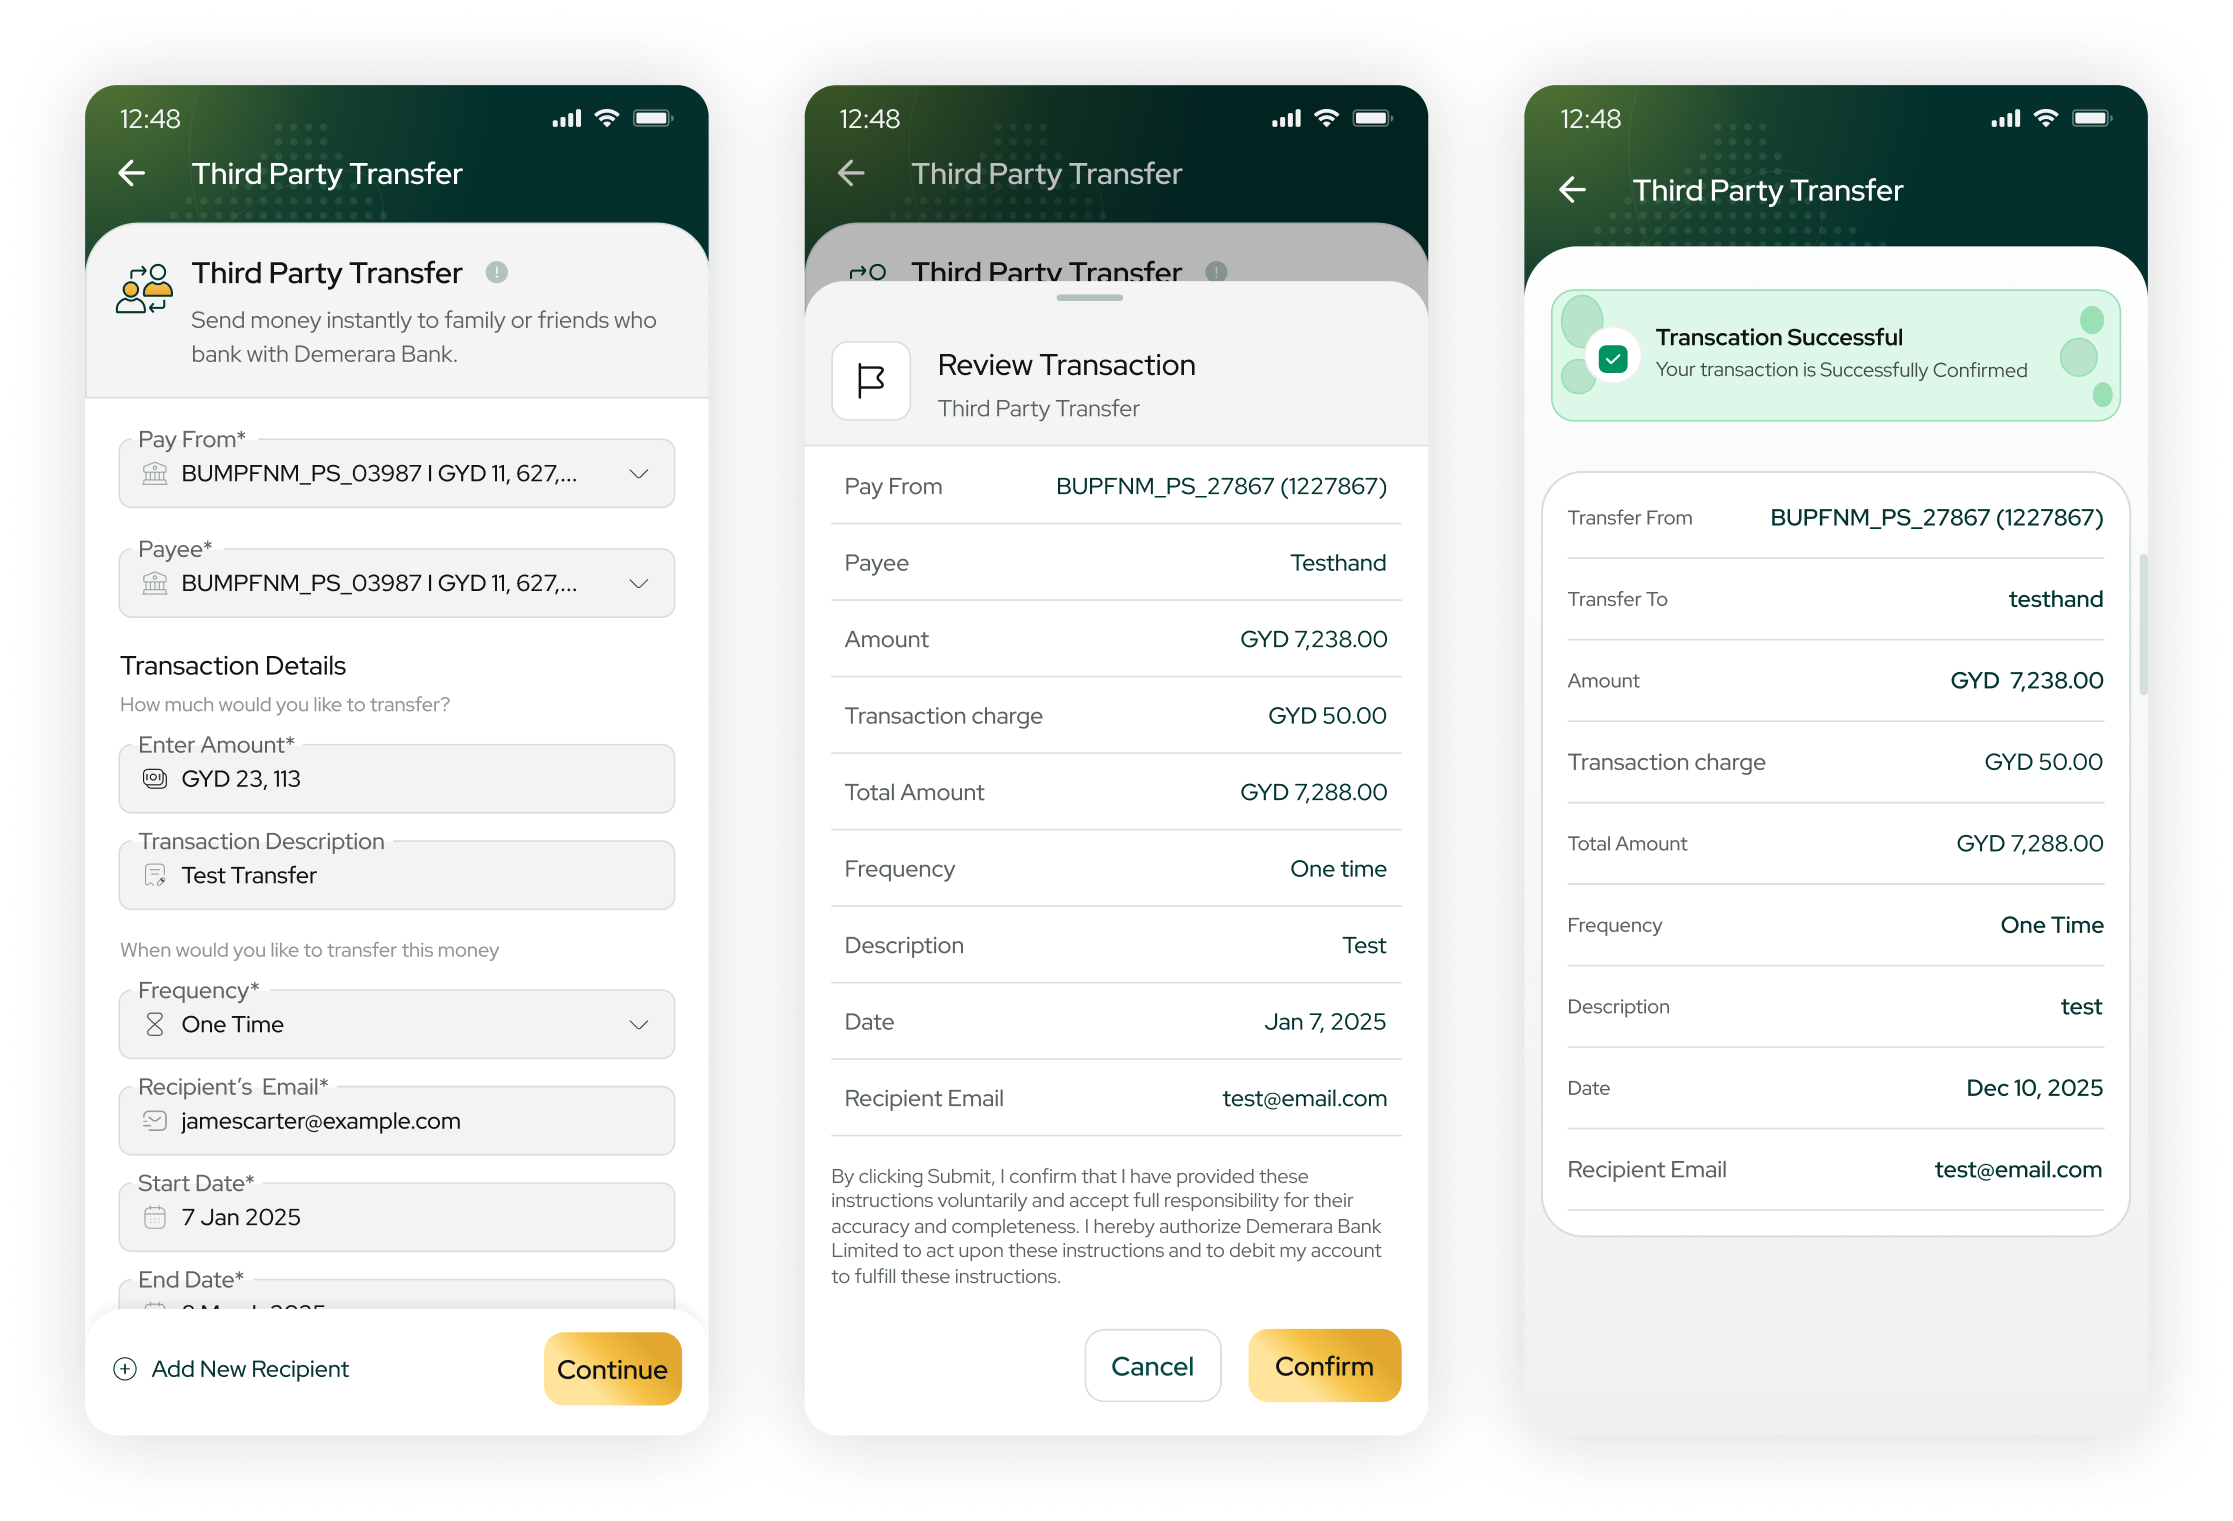
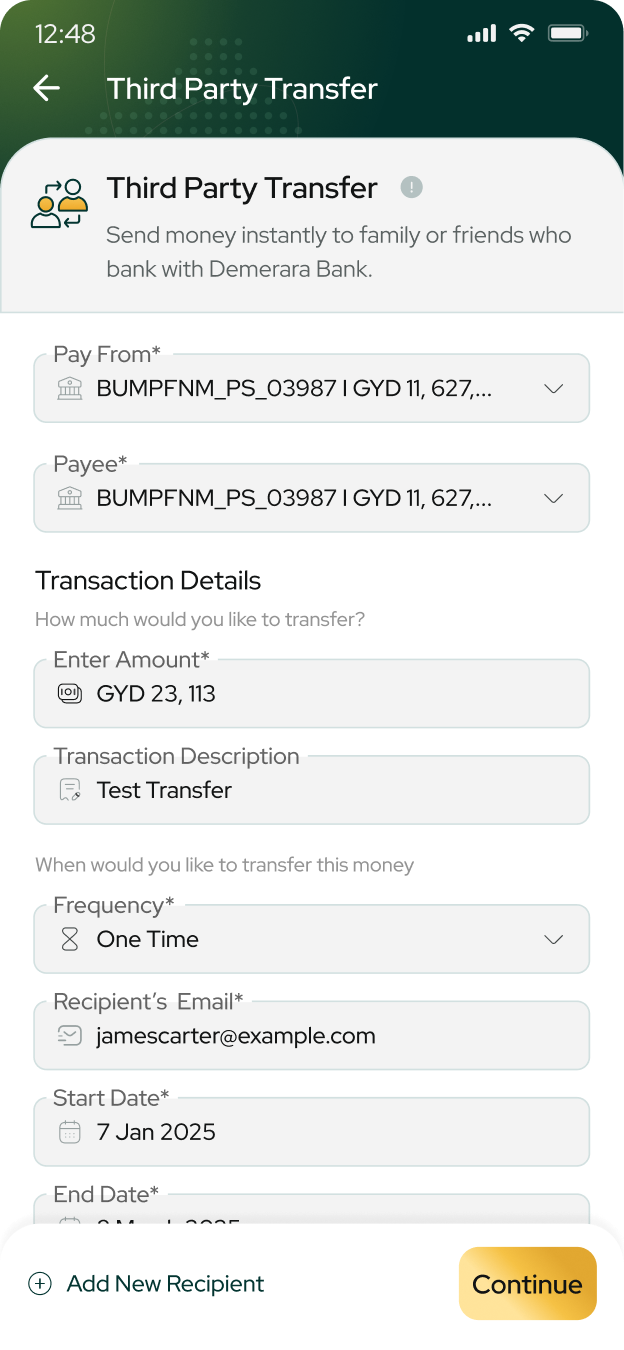
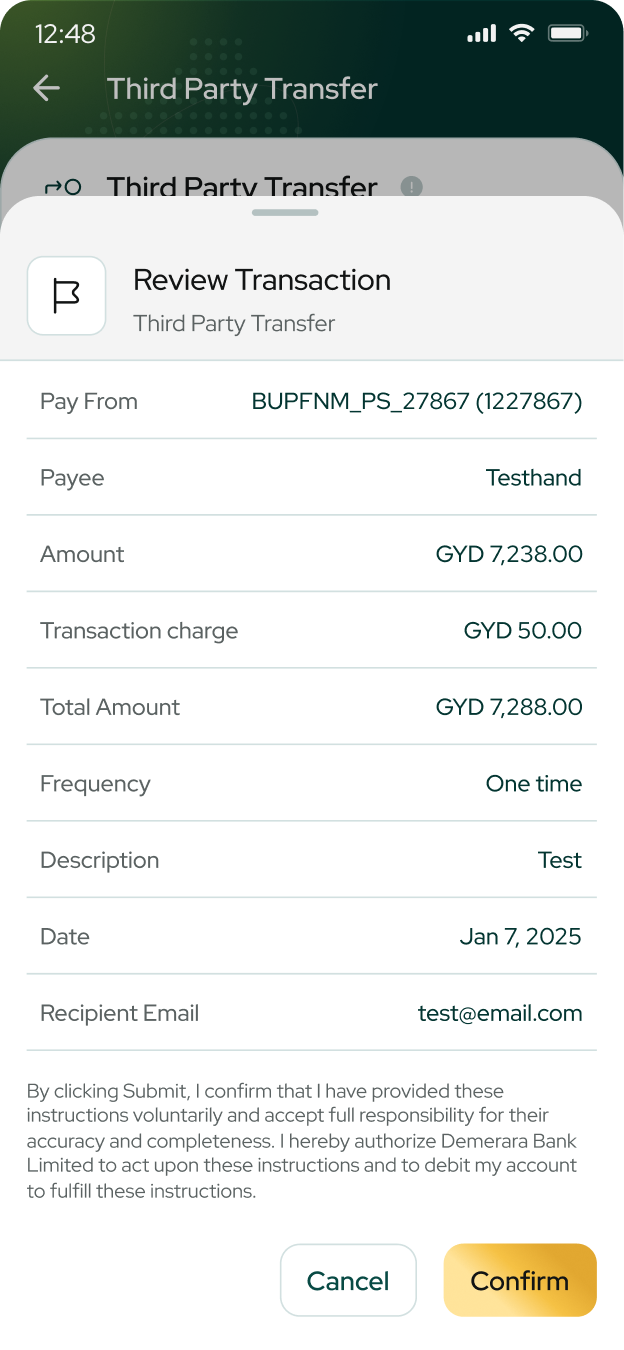
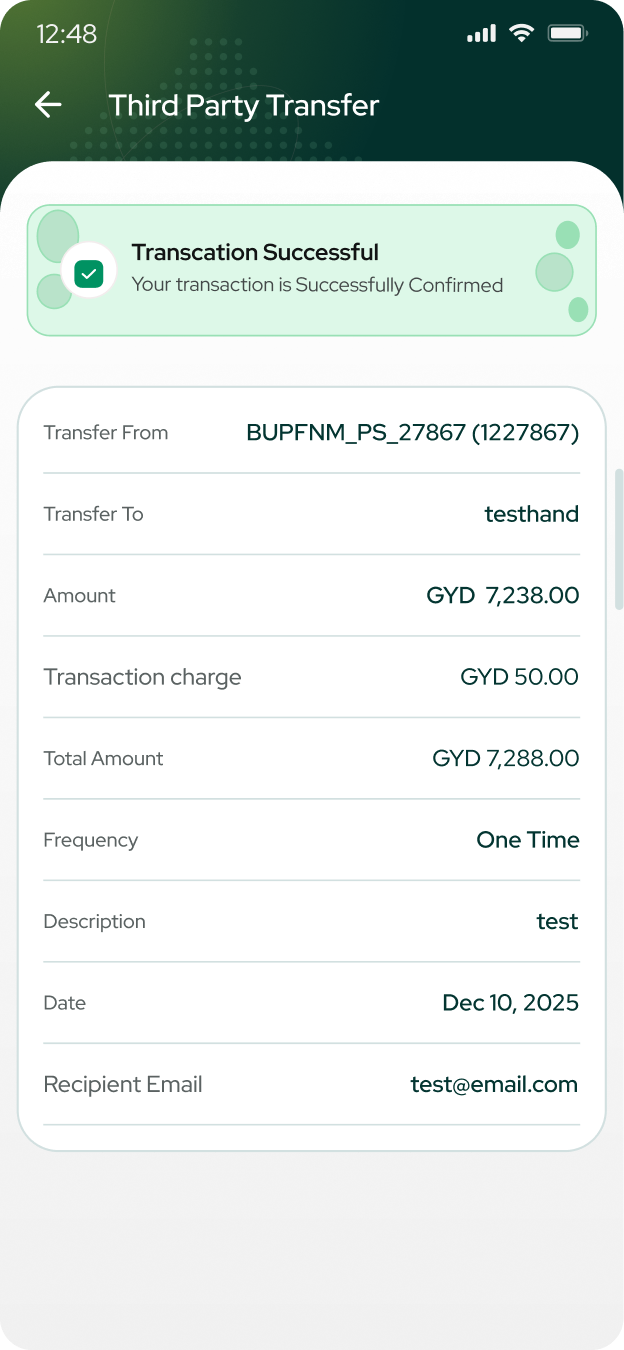
Third-party transfer: form, review and success screens
Transfer formTransfer reviewTransfer success

Swipe to see each screen →

21The solution

Self-Service & Tools

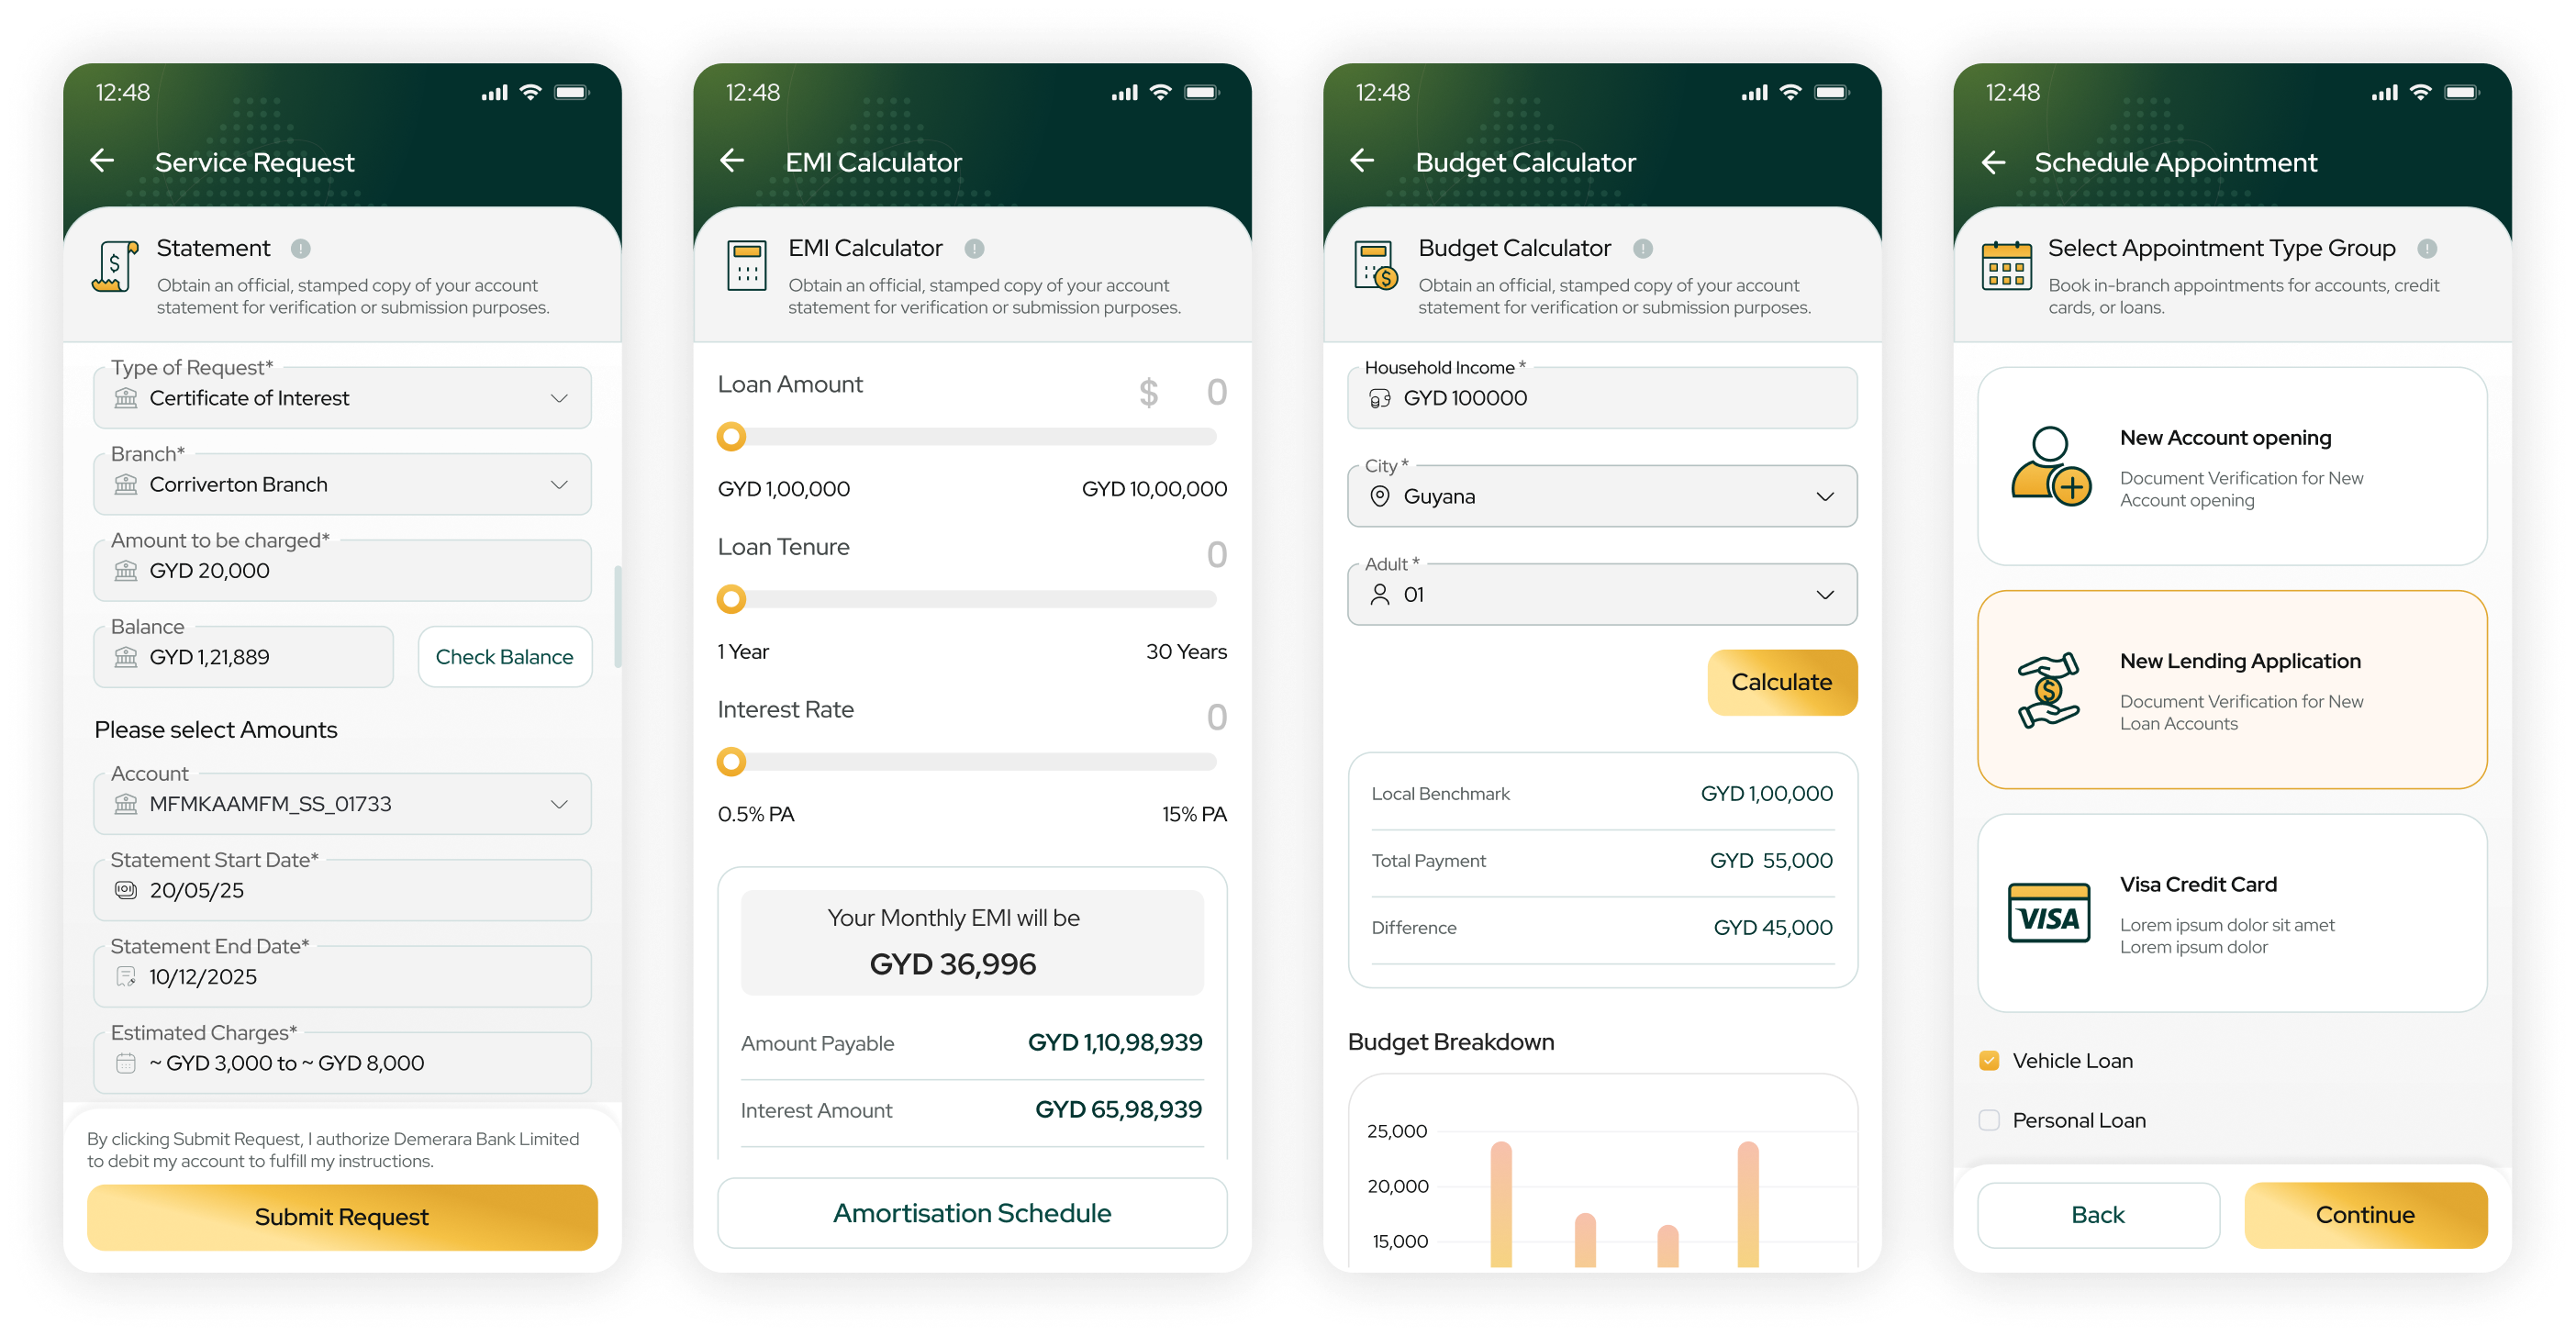
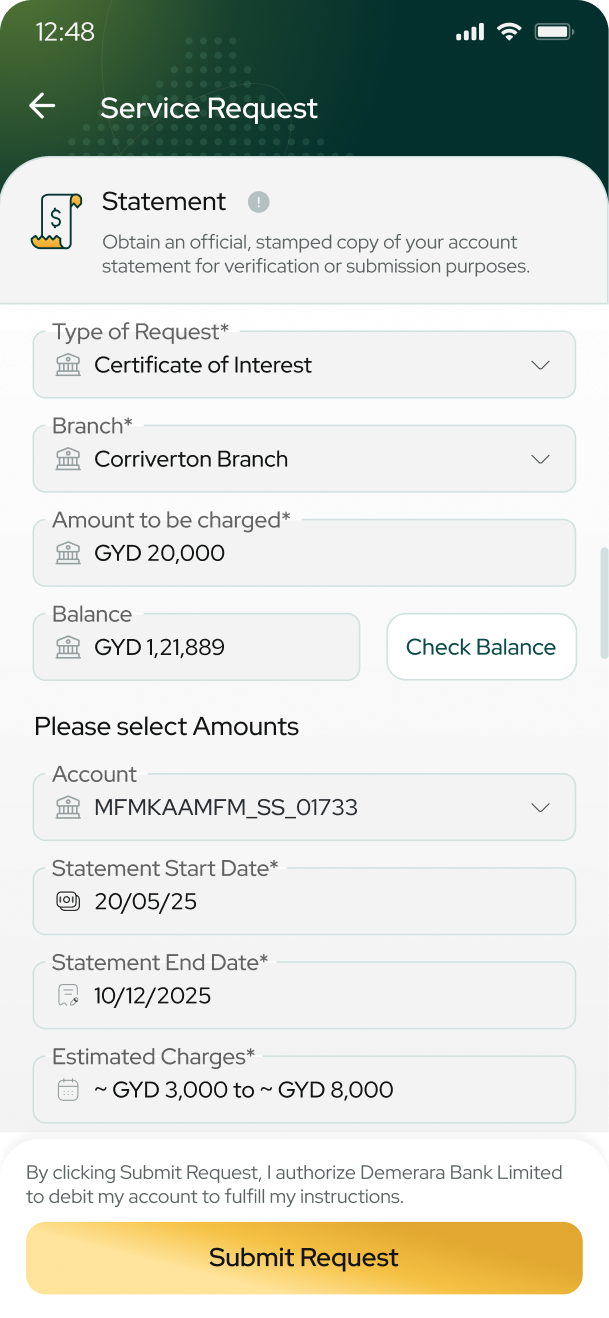
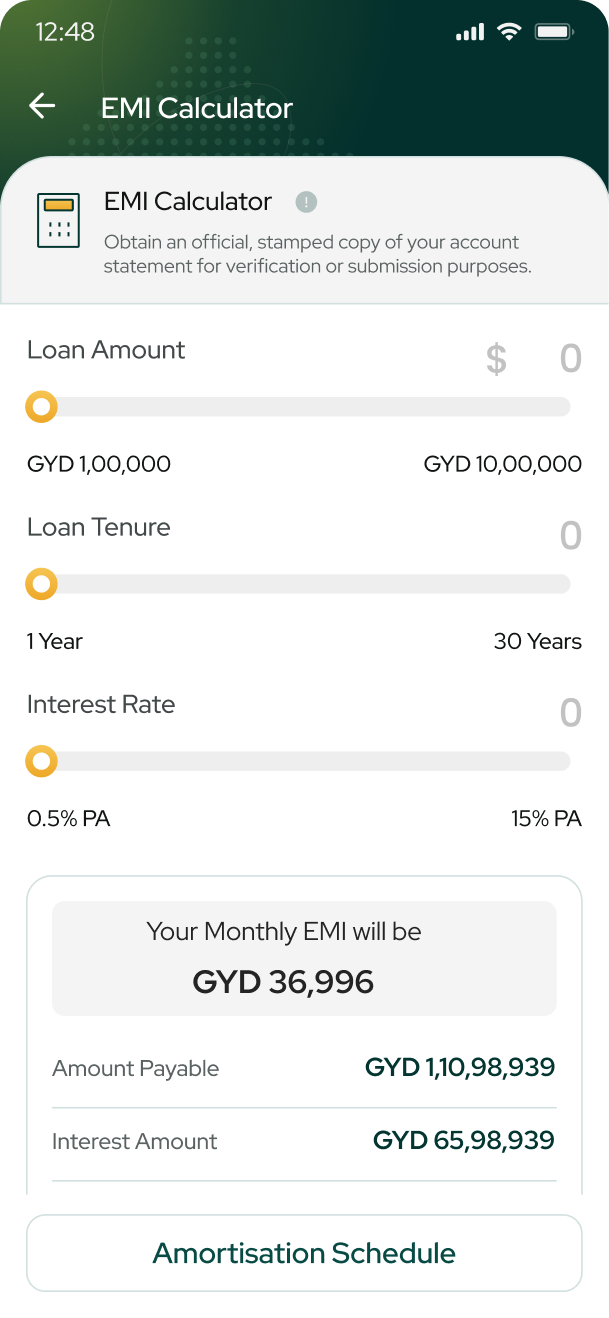
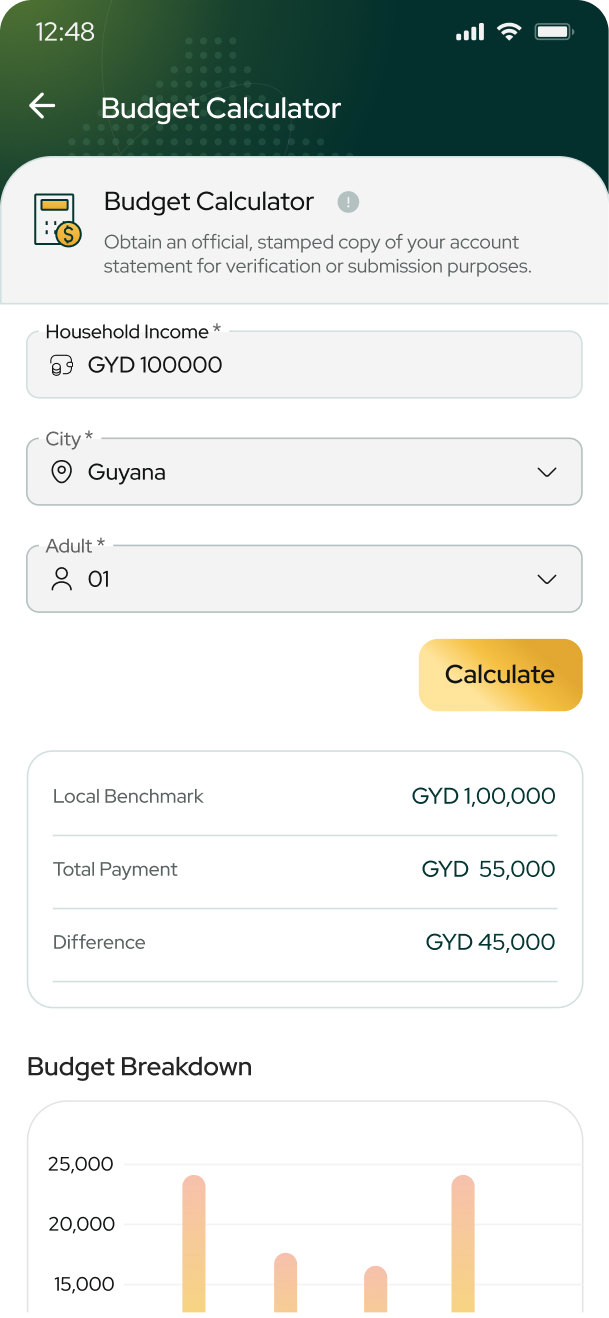
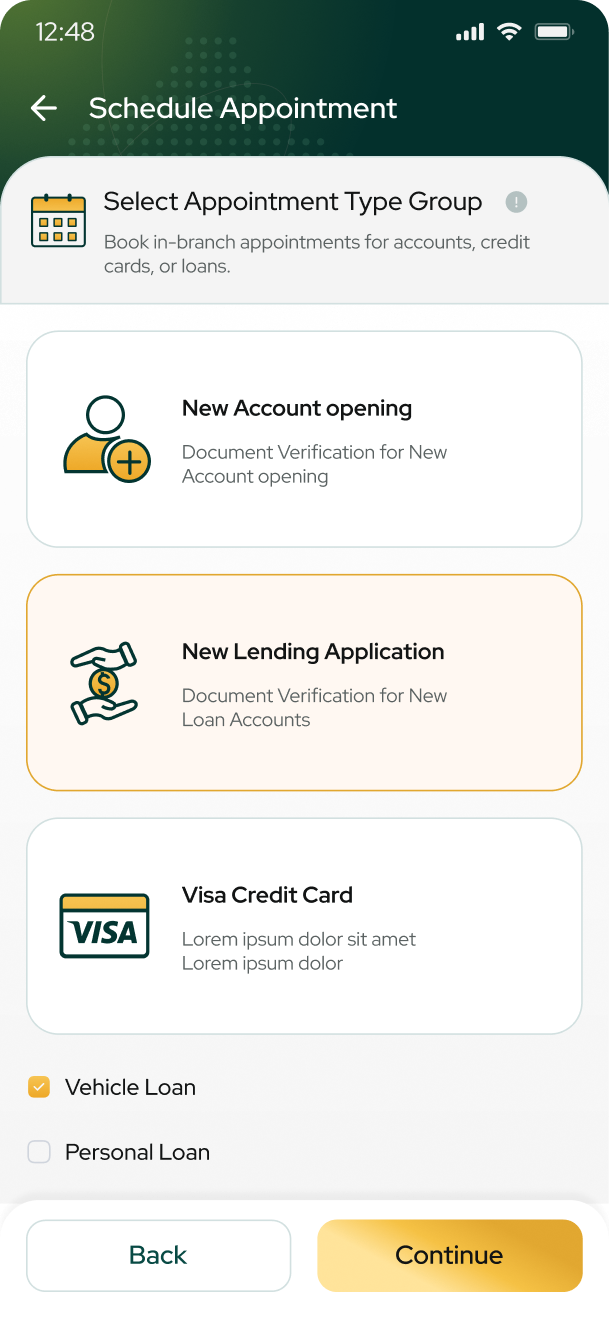
Service request, EMI calculator, budget calculator and appointment booking screens
Service request screenEMI calculatorBudget calculatorSchedule appointment screen

Swipe to see each screen →

22Outcome

Impact

The redesign delivered measurable gains against exactly the problems it set out to solve.

60%up

Increase in task completion

Transfers, bill payments and account tasks are faster to finish.

35%down

Reduction in support queries

Clearer navigation and real-time status cut repeat questions.

90%up

Improvement in user trust & confidence

Visible security and a modern interface raised confidence.

23Appendix

Supporting Research

The picture gradually became clear: the task was to turn Guyana’s digital momentum into a banking experience people actually trust.

01)

Connected, but banking the old way. 81.7% are online and mobile-money accounts have tripled since 2020, yet about 4 in 10 adults have no bank account.

02)

Distance is the real barrier. 72.5% live rurally, and one July 2026 letter to Kaieteur News reported four-hour bank queues. Every task in the app saves a trip.

03)

The bar for digital is rising. A national payment platform was called for in March 2026, and FAST PAY real-time payments were announced for June 2026.

Reference and Resources